If you have orders to Fort George G. Meade, a practical first question is: will your 2026 BAH stretch farther renting or buying? This guide covers MD133 basics, published BAH next to nearby asking rents, full costs on both sides, and a decision framework-not advice-for talks with a lender, finance office, and local agent.
By Scott Smolen | The Scott Smolen Team at RE/MAX Leading Edge
Fort Meade VA Loan Guide: What PCS Buyers Should Know Before They Shop
If you have orders to Fort George G. Meade - or you already live near base and are ready to buy - a VA loan is often the strongest path into Anne Arundel County and nearby communities. This evergreen guide walks through eligibility, full entitlement versus county limits, funding-fee basics, appraisals and Minimum Property Requirements (MPRs) around Odenton-Fort Meade, and why working with a local VA-experienced lender can matter as much as the rate sheet.
By Scott Smolen | The Scott Smolen Team at RE/MAX Leading Edge
By Scott Smolen, The Scott Smolen Team at RE/MAX Leading Edge
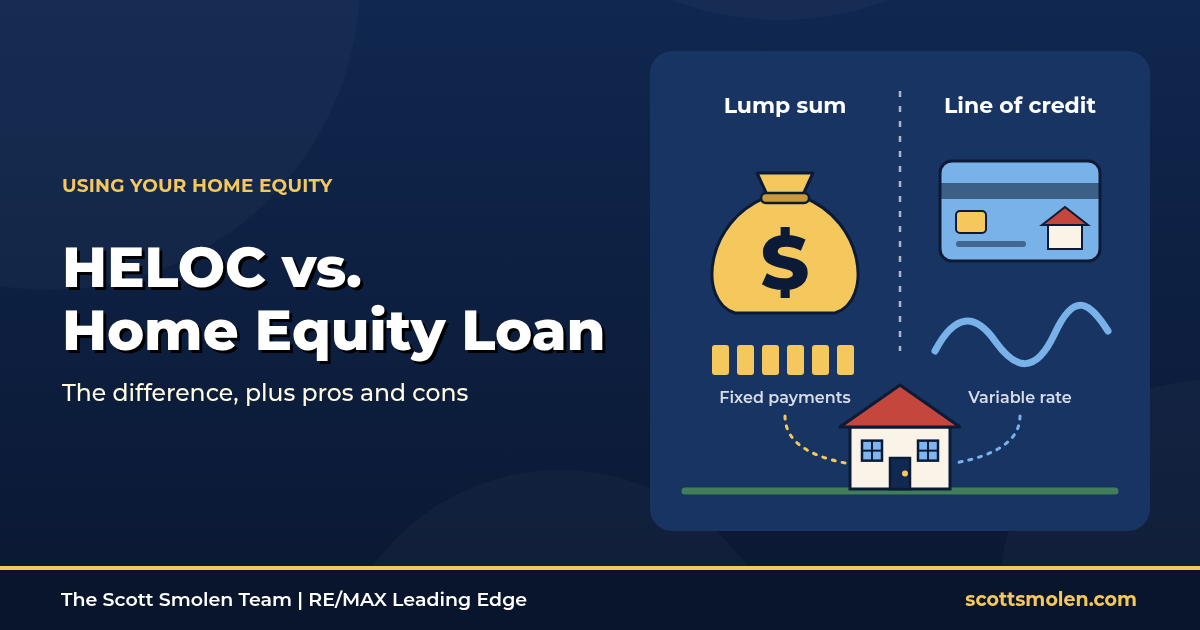
Short answer: A home equity loan gives you one lump sum, usually at a fixed rate with equal monthly payments, while a home equity line of credit (HELOC) is a revolving line you draw from as needed, usually at a variable rate, with payments based on what you owe. Both are second mortgages secured by your home, so missing payments can lead to foreclosure. A home equity loan generally suits a one-time cost with a known price; a HELOC generally suits costs that arrive in stages.
Scott Smolen is a local Realtor helping buyers and sellers in Crofton, Odenton, Gambrills, Bowie, Severn and the Fort Meade area. With 30-year mortgage rates at 7.32% (Freddie Mac, October 22, 2026), many Anne Arundel County owners who want cash for a renovation, tuition or debt payoff would rather keep their current first mortgage. A home equity loan or HELOC lets you do that. Here is how they differ, what the payments look like, and what to watch for.
What is the difference between a HELOC and a home equity loan?
The CFPB puts it simply: a home equity loan is a specific amount of money borrowed against your equity, and a HELOC is a line of credit, like a credit card, borrowed against your equity. If you already have a mortgage, either one is a second mortgage that you pay in addition to your first.
HELOC vs. home equity loan: side-by-side comparison
Feature
Home equity loan
HELOC
How you get the money
One lump sum up front
Draw as needed, up to your credit limit; repaying frees up credit again
Interest rate
Typically a fixed APR (adjustable rates are possible)
Typically a variable APR
Payments
Usually equal monthly payments over a fixed term
Based on the amount you owe; during the draw period you may pay interest only
Phases
One repayment term
A draw period, then a repayment period when you can no longer borrow
What the APR includes
Interest plus other credit costs
Interest only, not points or other financing charges
Can the lender change access?
Not applicable once funded
The lender may freeze or reduce the line in some cases, such as a significant drop in home value
Collateral
Your home
Your home
Best fit
One-time, known cost (roof, debt payoff)
Staged or uncertain costs (phased renovation, tuition by semester)
How much equity can you borrow against?
Your equity is what your home is worth minus what you owe. The amount you can borrow and your rate depend on your income, credit history and the home's market value. The FTC notes that many lenders prefer that you borrow no more than 80% of the equity in your home.
Crofton example: a home worth $503,000 (Anne Arundel County's September 2026 median sales price, per Maryland REALTORS) with a $300,000 mortgage balance.
Equity = $503,000 - $300,000 = $203,000. At 80% of equity: $203,000 x 0.80 = $162,400.
Lenders use their own formulas, so treat this as a rough ceiling, not an approval.
What do the payments look like?
Freddie Mac does not publish average HELOC or home equity loan rates. To show the math with a published number, we use its 15-year fixed average of 6.68% (October 22, 2026). Home equity quotes are set by each lender and will differ, and a HELOC rate can change over time.
Monthly payment on $50,000 borrowed at an illustrative 6.68%: U.S. dollars
Option
How it is calculated
Monthly payment
Home equity loan, 15-year term
Fully amortizing, 180 payments
$440.52
Home equity loan, 10-year term
Fully amortizing, 120 payments
$572.33
HELOC during draw period, interest only
$50,000 x 6.68% / 12
$278.33
Same HELOC if its variable rate rises 1 point to 7.68%
$50,000 x 7.68% / 12
$320.00
HELOC repayment period, 20 years at 6.68%
Fully amortizing, 240 payments
$378.10
The math: Monthly payment = Loan x r / (1 - (1 + r)^-n), with r = 0.0668 / 12 = 0.0055667.
15-year home equity loan: $50,000 x 0.0055667 / (1 - 1.0055667^-180) = $440.52.
The interest-only HELOC payment is lower at first ($278.33), but it pays down nothing. When the draw period ends, the payment on the same $50,000 jumps to about $378.10 over 20 years, an increase of $99.77 a month.
What are the pros and cons of each?
Home equity loan
Pros: predictable payment, typically fixed rate; you know your total cost up front; keeps your existing first mortgage in place.
Cons: you pay interest on the full amount from day one, even money you have not spent yet; harder to borrow more later without a new loan; your home is collateral.
HELOC
Pros: borrow only what you need, when you need it; pay interest only on what you draw; reuse the line as you repay during the draw period.
Cons: variable rate means the payment can rise; payment shock when the draw period ends; the lender may freeze or reduce the line if your home's value falls significantly; your home is collateral.
Should you use home equity or a cash-out refinance?
A cash-out refinance replaces your whole first mortgage with a bigger one at today's rate. The MBA reports that only 23% of borrowers hold mortgage rates over 6%, so for most owners a refinance at a rate in the 7% range would raise the rate on their entire balance. A second loan leaves the low-rate first mortgage alone and charges today's pricing only on the new money. Veterans near Fort Meade and Odenton can ask a lender to compare a home equity loan with a VA cash-out refinance before deciding.
Three-day right to cancel. When your main home is the collateral, the FTC explains that you can generally cancel a home equity loan or HELOC within three business days, for any reason and without penalty. It does not apply to a vacation or second home.
HELOC disclosures. The lender must disclose the APR, the payment terms for the draw and repayment periods, its fees, other parties' fees, any variable-rate features, and give you a HELOC brochure.
Stability if you pay as agreed. The lender generally may not close your HELOC, demand faster repayment or change its terms, though it can freeze or reduce the line in specific situations.
Housing counseling. If you are struggling with your mortgage, the CFPB suggests talking with a HUD-approved housing counselor first; call (855) 411-2372.
Planning to sell in the next few years? A home equity loan or HELOC balance generally has to be paid off from your proceeds at settlement. Our seller guide covers how today's rates affect pricing, and Mortgage Broker vs. Bank explains how to shop the loan itself.
Frequently asked questions
What is the difference between a HELOC and a home equity loan?
A home equity loan is a lump sum, usually at a fixed rate with equal monthly payments. A HELOC is a revolving line of credit, usually at a variable rate, that you draw from as needed and repay based on what you owe. Both are secured by your home.
Is a HELOC or a home equity loan better?
A home equity loan generally fits a one-time cost with a known price and a borrower who wants a fixed payment. A HELOC generally fits costs that come in stages, as long as you can handle a payment that may rise with rates and when the draw period ends.
How much can I borrow with a home equity loan or HELOC?
It depends on your income, credit and home value. The FTC notes many lenders prefer you borrow no more than 80% of your equity. On a $503,000 home with a $300,000 balance, equity is $203,000 and 80% of that is $162,400.
What would the payment be on a $50,000 home equity loan?
At an illustrative 6.68% (Freddie Mac's 15-year fixed average on October 22, 2026), a $50,000, 15-year home equity loan is about $440.52 a month. An interest-only HELOC draw of $50,000 at the same rate is about $278.33 a month but pays down no principal.
Can a lender freeze my HELOC?
Yes, in some situations. The FTC explains that a lender may freeze or reduce a line of credit if your home's value drops significantly below the appraised amount or if the lender reasonably believes a material change in your finances will keep you from paying.
Can I cancel a home equity loan or HELOC after closing?
Generally yes, within three business days, if your main home is the collateral. The FTC says you must cancel in writing; the right does not apply to a vacation or second home.
Talk to a local lender before you decide
The right choice depends on your first-mortgage rate, how much you need, how quickly you will repay it and whether you may sell soon. Call The Scott Smolen Team at 301-651-1261.
The Scott Smolen Team at RE/MAX Leading Edge, 1655 Crofton Blvd, Suite 203, Crofton, MD 21114.
Disclaimer: This article is general information, not financial, tax or legal advice, and it is not a loan offer or rate quote. The 6.68% rate is used only to illustrate the math; home equity rates are set by each lender. Mortgage rates are Freddie Mac PMMS weekly averages as of October 22, 2026; Freddie Mac publishes new averages every Thursday. Confirm terms and costs with a licensed lender and consult a tax advisor about interest deductibility.
Sources:
CFPB, What is the difference between a Home Equity Loan and a Home Equity Line of Credit (HELOC)?: View official source (accessed October 19, 2026)
CFPB, What you should know about home equity lines of credit (HELOC brochure, PDF): View official source (accessed October 19, 2026)
FTC, Home Equity Loans and Home Equity Lines of Credit: View official source (accessed October 19, 2026)
Freddie Mac, Primary Mortgage Market Survey, U.S. weekly averages as of October 22, 2026: View official source (accessed October 23, 2026)
Mortgage Bankers Association, MBA Newslink, Chart of the Week: Mortgage Originations Forecast (October 16, 2026): View official source (accessed October 19, 2026)
Maryland REALTORS, Housing Statistics: September 2026 (Bright MLS data): View official source (accessed October 19, 2026)
CFPB, What is the difference between a mortgage interest rate and an APR?: View official source (accessed October 19, 2026)
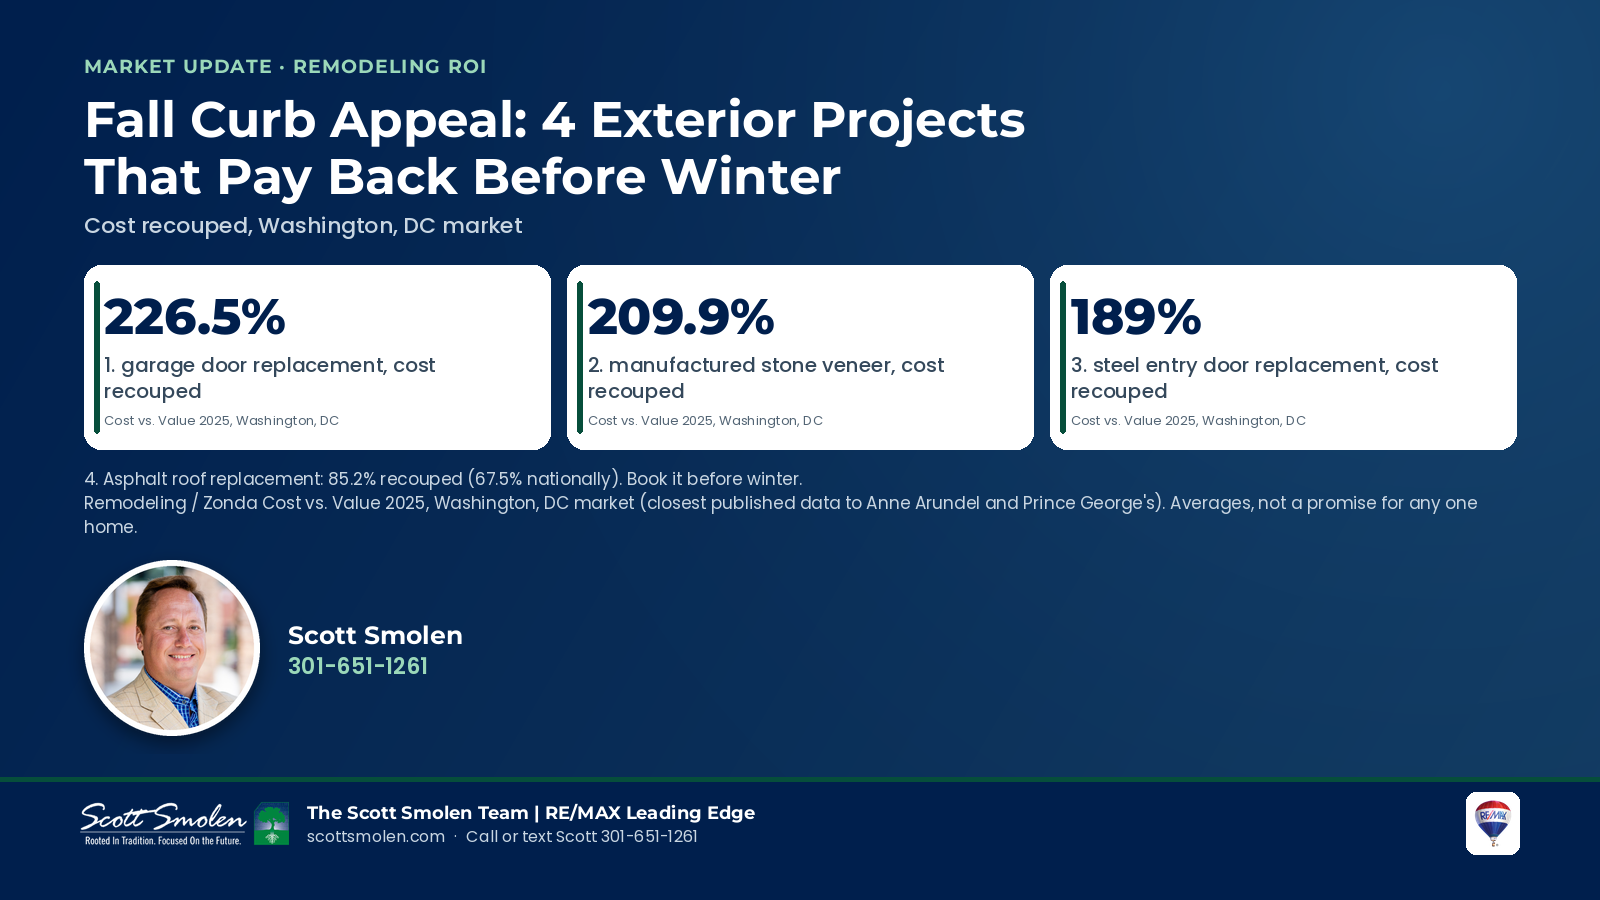
Every October I notice the same thing driving through Crofton, Odenton, Gambrills and Bowie. Once the leaves come down, the front of every house is on full display. The garage door, the front entry, the roofline and the siding are suddenly the first thing anyone sees, whether that’s a neighbor walking past or a buyer scrolling listing photos on a Sunday night.
If you’re thinking about selling this winter or early next spring, that’s good news. The exterior projects with the strongest payback tend to be some of the least expensive ones. The catch is timing: most of this work needs to be finished before cold weather shuts down outdoor projects.
Here’s what the latest numbers say and how I’d think about them for a home in our area.
By Scott Smolen, The Scott Smolen Team at RE/MAX Leading Edge
Short answer: Most Maryland first-time buyers follow the same path: set a budget, take a homebuyer education class, get preapproved, choose an agent, make an offer, finish inspections and the appraisal, then settle. In Anne Arundel County, where the September 2026 median sale price was $503,000, principal and interest at Freddie Mac's 7.32% average (as of October 22, 2026) runs about $3,110 a month with 10% down. The Maryland Mortgage Program can add down payment help, such as a $6,000 or 3% to 5% deferred, zero-interest loan, for buyers who meet its income and price limits.
Scott Smolen is a local Realtor helping buyers and sellers in Crofton, Odenton, Gambrills, Bowie, Severn and the Fort Meade area. This guide walks through the Maryland home buying process, a checklist you can print, Anne Arundel County payment math, ways to save for a down payment and the state's Maryland Mortgage Program. We will update the numbers as new data comes out.
What are the steps to buying a home in Maryland?
Every purchase is different, but most first-time buyers move through these eight steps in roughly this order.
1. Set your budget and check your credit
Add up your savings, monthly debts and income. Lenders look at your debt-to-income ratio, which the CFPB defines as all of your monthly debt payments divided by your gross monthly income. Different loans and lenders set different limits.
2. Take a homebuyer education class
If you plan to use the Maryland Mortgage Program, an approved class is required before approval, and the certificate must be issued within 12 months before settlement. Classes can also point you to assistance you did not know about.
Since August 17, 2024, buyers working with a REALTOR are asked to sign a written buyer agreement before touring a home, in person or virtually. NAR notes these agreements, including compensation, are negotiable. Read it carefully and ask questions before you sign.
5. Tour homes and make an offer
Your agent pulls comparable sales, helps you set a price and terms, and explains deposits and contingencies. In a competitive pocket, terms can matter as much as price.
6. Inspect the home and complete the appraisal
HUD reminds buyers that an appraisal estimates value for the lender and is not a home inspection. A home inspection happens only if you arrange one, and asking early may let you make the contract contingent on the results.
7. Get final loan approval and review your Closing Disclosure
Your lender must give you the Closing Disclosure at least three business days before you close. Compare it with your Loan Estimate and ask about anything that changed.
8. Do a final walkthrough and settle
Confirm the home's condition, then sign at settlement. Before wiring any money, verify the instructions by phone with a number you already trust. The CFPB warns that scammers send fake wiring instructions by email.
A printable buying-a-home checklist
Print this page or save it as a PDF and check off each item as you go.
First-time buyer checklist: tasks by stage, with a box to check
Done
Stage
Task
[ ]
Budget
List monthly income and debts; estimate your debt-to-income ratio.
[ ]
Budget
Set a savings target for down payment, closing costs and a cash cushion.
[ ]
Education
Complete an approved homebuyer education class and keep the certificate.
[ ]
Financing
Gather pay stubs, W-2s or tax returns, bank statements and photo ID.
[ ]
Financing
Apply with at least two lenders and compare Loan Estimates.
[ ]
Financing
Ask an MMP-approved lender whether you qualify for down payment assistance.
[ ]
Agent
Interview agents; review and sign a written buyer agreement.
[ ]
Search
Write down must-haves, nice-to-haves and deal-breakers.
[ ]
Offer
Review comparable sales, price, deposit, contingencies and settlement date.
[ ]
Under contract
Schedule the home inspection; consider radon and other tests.
[ ]
Under contract
Shop for homeowners insurance and send proof to the lender.
[ ]
Closing
Review the Closing Disclosure at least three business days before closing.
[ ]
Closing
Verify wiring instructions by phone using a number you already trust.
[ ]
Closing
Do the final walkthrough; bring ID and certified funds as instructed.
How much house can I afford in Anne Arundel County?
Two numbers anchor the math. Maryland REALTORS reports, from Bright MLS data, that Anne Arundel County's median sale price was $503,000 in September 2026, up 2.4% from $490,990 a year earlier. Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed average at 7.32% as of October 22, 2026. Here is what that median price costs each month at different down payments.
Anne Arundel County median ($503,000) at 7.32% for 30 years: principal and interest in U.S. dollars per month
Down payment
Cash down
Loan amount
Monthly principal and interest
3%
$15,090
$487,910
$3,352
5%
$25,150
$477,850
$3,282
10%
$50,300
$452,700
$3,110
20%
$100,600
$402,400
$2,764
Worked example: checking the payment against income. With 10% down, principal and interest is about $3,110. Add $500 of other monthly debt payments and the total is $3,610. On a gross monthly income of $12,000, that is about 30% of income before property taxes, homeowners insurance, mortgage insurance and any HOA dues are added.
Rate sensitivity (hypothetical). If the rate were one point lower, at 6.32%, the same $452,700 loan would cost about $2,808 a month, roughly $302 less.
These figures are principal and interest only, use a national average rate for borrowers with strong credit and 20% down, and assume a 30-year fixed loan. Your quote can be higher or lower. For a fuller monthly budget, see our true cost of owning a home in Anne Arundel County.
How can I save for a down payment faster?
NAR's 2025 Profile of Home Buyers and Sellers found that first-time buyers most often used personal savings (59%), followed by financial assets such as a 401(k) or stocks (26%) and gifts or loans from family and friends (22%). Strategies that help:
Know your real target. HUD says FHA's minimum required investment is 3.5% in most cases, and Fannie Mae's HomeReady allows as little as 3% down. Your target may be smaller than you think, but plan for closing costs too.
Automate it. Send a set amount to a separate savings account each payday so the money is out of sight.
Use gifts the right way. HUD notes the FHA minimum investment can come from your own funds, gifts, second mortgages and grants through assistance programs. Ask your lender how gifts must be documented before money moves.
Layer in assistance. Maryland Mortgage Program loans, MMP Partner Match funds, employers, builders and local governments may all offer help (see the next section).
Clear student debt with SmartBuy. Maryland SmartBuy can pay off up to 15% of the purchase price (maximum $25,000) in qualifying student debt at closing, as a zero-interest loan forgiven after 5 years in the home.
Do not drain everything. Keep a cash cushion after closing. Note that MMP eligibility can be affected if liquid assets exceed 20% of the purchase price.
What down payment assistance is available through the Maryland Mortgage Program?
The Maryland Mortgage Program (MMP) is run by the Maryland Department of Housing and Community Development (DHCD). It offers 30-year fixed-rate loans through approved lenders, and most of its products include down payment assistance. You generally must occupy the home as your primary residence, not own other residential property, complete homebuyer education and meet income, credit score and purchase price limits.
Maryland Mortgage Program options for first-time buyers (as listed by MMP, October 2026)
Product
Who it is for
Down payment assistance
1st Time Advantage Direct
First-time buyers
No MMP assistance; usually MMP's most competitive rate. Outside assistance may be used.
1st Time Advantage 6000
First-time buyers
$6,000 zero-interest deferred second loan for down payment and closing costs; eligible for Partner Match up to $2,500.
1st Time Advantage 3%, 4% or 5%
First-time buyers
Zero-interest deferred loan equal to 3%, 4% or 5% of the first mortgage.
HomeStart
Income at or below 50% of area median income
Zero-interest, 30-year deferred loan equal to 6% of the first mortgage.
Flex 6000 or Flex 3%
First-time or repeat buyers
$6,000 or 3% of the first mortgage, zero-interest and deferred.
Maryland SmartBuy
Buyers with at least $1,000 of student debt; 720 minimum credit score
Up to 15% of the price (maximum $25,000) to pay off student debt, forgiven after 5 years.
The deferred assistance loans carry no monthly payment, but they become due when the first mortgage ends, for example when you sell, refinance or pay off the loan. A $450,000 first mortgage with a 3% assistance loan, for example, would come with $13,500 of deferred assistance.
2026 MMP limits for Anne Arundel County (effective June 24, 2026): U.S. dollars
Limit
Non-Targeted Area
Targeted Area
Household income, 1 or 2 people
$140,759
$164,520
Household income, 3 or more people
$161,873
$191,940
Maximum acquisition cost
$782,118
$955,922
Anne Arundel County is a partially targeted county, so the limits depend on the address. MMP's online mapper shows whether a property is in a Targeted Area, and an MMP-approved lender can confirm which products you qualify for.
What should first-time buyers know before making an offer?
Before you shop
Get preapproved before you tour so you know your price range.
Budget for closing costs and moving, not just the down payment.
Ask your lender before opening new credit or changing jobs.
When you find the home
Look at the full monthly cost: taxes, insurance and HOA dues.
Keep the inspection; it protects you from surprises.
Read every document, and ask until you are comfortable.
Do I need 20% down to buy my first home in Maryland?
No. Many first-time buyers put down far less. NAR's 2025 Profile of Home Buyers and Sellers reports a 10% median down payment for first-time buyers. HUD says FHA's minimum required investment is 3.5% in most cases, Fannie Mae's HomeReady allows as little as 3% down, and VA-backed purchase loans often need no down payment when the price is not above the appraised value. A smaller down payment usually means a larger loan and, on many loans, mortgage insurance.
How much house can I afford in Anne Arundel County?
Start with the payment, not the price. At the county's $503,000 September 2026 median and Freddie Mac's 7.32% 30-year average (October 22, 2026), principal and interest is about $3,352 a month with 3% down, $3,110 with 10% down and $2,764 with 20% down. Taxes, insurance, mortgage insurance and HOA dues come on top. A lender will compare your total monthly debts with your gross income (your debt-to-income ratio) before approving a loan.
Who counts as a first-time homebuyer for the Maryland Mortgage Program?
The Maryland Mortgage Program treats someone who has not owned residential property for three years or more as a first-time homebuyer. Honorably discharged veterans using their exemption for the first time, and buyers purchasing in a Targeted Area, may also qualify for certain products. An MMP-approved lender confirms eligibility.
How much down payment assistance can I get through the Maryland Mortgage Program?
It depends on the product. The 1st Time Advantage line includes a $6,000 assistance loan and loans equal to 3%, 4% or 5% of the first mortgage, all as zero-interest deferred second liens. HomeStart offers 6% for households at or below 50% of area median income. On the 6000 products, MMP matches assistance from an approved Partner up to $2,500. The deferred loan is due when the first mortgage ends, such as at a sale or refinance.
What are the 2026 Maryland Mortgage Program limits in Anne Arundel County?
Under the limits effective June 24, 2026, the household income limit outside Targeted Areas is $140,759 for 1 or 2 people and $161,873 for 3 or more, and the maximum acquisition cost is $782,118. In Targeted Areas the limits are $164,520 and $191,940, with a $955,922 maximum acquisition cost. Limits change, so confirm them with an MMP-approved lender.
Do I need a homebuyer education class?
For the Maryland Mortgage Program, yes. MMP requires an approved homebuyer education class before approval, and the certificate must be issued within 12 months before settlement. Fannie Mae's HomeReady also requires homeownership education when all occupying borrowers are first-time buyers. Taking the class before you sign a contract is a good idea.
Get your first-time buyer plan
Tell us your budget, timing and the towns you like, and we will map out next steps, from your financing timeline to the homes that fit. Call The Scott Smolen Team at 301-651-1261.
The Scott Smolen Team at RE/MAX Leading Edge, 1655 Crofton Blvd, Suite 203, Crofton, MD 21114.
Disclaimer: This article is general information, not financial, tax or legal advice, and it is not a loan offer, rate quote or commitment to lend. Program terms, limits, rates and market data change often. Mortgage rates are Freddie Mac PMMS weekly averages as of October 22, 2026; Freddie Mac publishes new averages every Thursday. Payment examples are principal and interest only and are for illustration. Confirm eligibility and costs with a licensed mortgage lender and, for legal questions, a Maryland attorney.
Sources:
Freddie Mac, Primary Mortgage Market Survey, U.S. weekly averages as of October 22, 2026: View official source (accessed October 22, 2026)
Maryland REALTORS, Housing Statistics: September 2026 (Bright MLS data, current as of October 12, 2026): View official source (accessed October 19, 2026)
Maryland Mortgage Program (DHCD), MMP 1st Time Advantage: View official source (accessed October 19, 2026)
Maryland Mortgage Program (DHCD), Down Payment Assistance: View official source (accessed October 19, 2026)
Maryland Mortgage Program (DHCD), MMP Flex Loans: View official source (accessed October 19, 2026)
Maryland Mortgage Program (DHCD), Loan Eligibility: View official source (accessed October 19, 2026)
Maryland Mortgage Program (DHCD), 2026 Income Limits and Maximum Acquisition Costs (effective June 24, 2026): View official source (accessed October 19, 2026)
Maryland Mortgage Program (DHCD), Homebuyer Education: View official source (accessed October 19, 2026)
Maryland Mortgage Program (DHCD), Maryland SmartBuy Loan: View official source (accessed October 19, 2026)
NAR, First-Time Home Buyer Share Falls to Historic Low of 21%, Median Age Rises to 40 (2025 Profile of Home Buyers and Sellers): View official source (accessed October 19, 2026)
NAR, Consumer Guide to Written Buyer Agreements: View official source (accessed October 19, 2026)
Costumes out, everybody! This is one of the busiest Halloween weekends of the year around here, with a hometown parade in Crofton, trunk-or-treats in Bowie and Odenton, and the very last weekend of the Maryland Renaissance Festival. Here's what we found, local towns first.
By Scott Smolen, The Scott Smolen Team at RE/MAX Leading Edge
Short answer: Probably not by much in the next year, based on the latest official forecasts. Freddie Mac's 30-year fixed average was 7.32% as of October 22, 2026, and the October 2026 forecasts from Fannie Mae (7.4% for the fourth quarter of 2026 and 7.5% for every quarter of 2027) and the Mortgage Bankers Association (7.3% this quarter, easing to 7.1% by late 2027) both keep rates above 7%. Rates still move week to week, so Maryland buyers should budget for today's payment and treat a future refinance as a bonus, not a plan.
Scott Smolen is a local Realtor helping buyers and sellers in Crofton, Odenton, Gambrills, Bowie, Severn and the Fort Meade area. This outlook pulls together the latest Freddie Mac rate survey, the newest Fannie Mae and MBA forecasts and Anne Arundel County sales data from Maryland REALTORS, then shows what the numbers mean for a real monthly payment. We refresh it each month after the new releases come out.
What are mortgage rates today?
Freddie Mac's Primary Mortgage Market Survey (PMMS) is the most widely cited weekly average. For the week ending October 22, 2026, the 30-year fixed averaged 7.32%, down from 7.40% the prior week, and the 15-year fixed averaged 6.68%, down from 6.71%. A year earlier, the 30-year averaged 6.19% and the 15-year averaged 5.44%.
Freddie Mac PMMS weekly averages: percent, U.S. conventional purchase loans
Week of
30-year fixed
15-year fixed
October 22, 2026 (latest)
7.32%
6.68%
October 15, 2026
7.40%
6.71%
September 3, 2026
6.71%
6.04%
February 26, 2026 (2026 low for the 30-year)
5.98%
5.44%
One year ago (October 2025)
6.19%
5.44%
In other words, the 30-year average has climbed about 1.3 percentage points from its February low, and nearly half of that rise (0.61 point) came after early September. The PMMS reflects borrowers with good to excellent credit, a 20% down payment and a home purchase loan on an owner-occupied single-family home, so your own quote can be higher or lower.
Are mortgage rates expected to drop?
Not meaningfully, according to the two forecasts we track. Both were published in October 2026 and both are built on Freddie Mac's 30-year rate.
2026 mortgage rate forecast: 30-year fixed, quarterly average in percent
Quarter
Fannie Mae (Oct. 12, 2026)
MBA (Oct. 11, 2026)
Q3 2026
6.7%
6.7%
Q4 2026
7.4%
7.3%
Q1 2027
7.5%
7.2%
Q2 2027
7.5%
7.2%
Q3 2027
7.5%
7.2%
Q4 2027
7.5%
7.1%
Fannie Mae notes that its interest rate forecasts are based on rates as of September 30, 2026, before the early October run-up. The MBA expects rates to "come down from their recent peaks" but to stay on a higher path than it previously forecast, and its table shows the 30-year near 7.0% by the end of 2028. Forecasts change every month, so treat these as the current best estimates, not promises.
Will mortgage rates go down in 2026?
With about ten weeks left in the year, neither forecast calls for a drop before year-end. Fannie Mae puts the fourth-quarter 2026 average at 7.4% and the MBA at 7.3%, compared with a first-quarter 2026 average of 6.1% in both forecast tables. A sharp drop would likely require a surprise, such as much cooler inflation data or a big rally in the bond market.
The Federal Reserve's September rate hike made headlines, but the Fed does not set mortgage rates directly. Thirty-year rates follow the bond market, inflation expectations and the economic outlook. We explain that in The Fed Raised Rates: Does That Mean Mortgage Rates Are Going Up?
When will mortgage rates drop?
Nobody knows the date, and anyone who promises one is guessing. Based on the October 2026 forecasts, the MBA sees only a gradual slide (7.2% through most of 2027, 7.1% in late 2027), while Fannie Mae sees rates holding near 7.5% through 2027. What to watch each month:
The weekly Freddie Mac PMMS release every Thursday at 12 p.m. ET.
Monthly inflation reports and the 10-year Treasury yield, which longer-term mortgage rates tend to track.
Each new Fannie Mae and MBA forecast. We update this page when they change.
What does a rate change mean for a Maryland mortgage payment?
Here is a real Anne Arundel County example. Maryland REALTORS reports the county's September 2026 median sales price at $503,000. With 20% down ($100,600), the loan is $402,400. The table shows principal and interest only; taxes, insurance and any HOA dues are extra.
Monthly principal and interest on a $402,400, 30-year fixed loan: U.S. dollars
Rate scenario
Rate
Monthly P&I
vs. today
Freddie Mac 30-year, Oct. 22, 2026
7.32%
$2,764.21
-
Fannie Mae 2027 forecast
7.50%
$2,813.64
+$49.43
MBA Q4 2026 forecast
7.30%
$2,758.74
-$5.47
MBA Q4 2027 forecast
7.10%
$2,704.26
-$59.95
Freddie Mac 30-year, one year ago
6.19%
$2,461.96
-$302.25
Freddie Mac 30-year, 2026 low (Feb. 26)
5.98%
$2,407.42
-$356.79
Freddie Mac 15-year, Oct. 22, 2026 (15-year term)
6.68%
$3,545.28
+$781.07
The math: Monthly payment = Loan x r / (1 - (1 + r)^-n), where r is the annual rate divided by 12 and n is the number of monthly payments.
At 7.32%: r = 0.0732 / 12 = 0.0061; n = 360; (1 + r)^-360 = 0.11199.
Payment = $402,400 x 0.0061 / (1 - 0.11199) = $2,764.21 per month.
The takeaway: the MBA's late-2027 forecast would save about $59.95 a month on this loan. That is real money, so weigh it against what could happen to prices and your rent while you wait. Going all the way back to the 2026 low would save about $356.79 a month, but neither forecast expects that.
How can you get the best mortgage rate today?
The "best mortgage rates today" are the ones quoted to you, on the same day, for the same loan. A few steps help in any market:
Compare at least two or three Loan Estimates on the same day. Rates change daily, so same-day quotes are the only fair comparison. Ask each lender for a Loan Estimate so you can compare costs.
Look at the APR and the points, not just the rate. A lower rate that costs two points may not be the better deal if you plan to move or refinance.
Protect your credit and down payment. The PMMS average reflects strong credit and 20% down; weaker credit or less down usually prices higher.
Ask about VA loans if you serve or served. We often work with VA buyers near Fort Meade, Odenton and Crofton. Compare VA quotes with conventional quotes from the same lender.
Already own a low-rate home? Tapping equity with a second loan may beat a cash-out refinance. Ask a qualified lender to explain home equity loans, HELOCs, and any age-based mortgage options that may apply.
What do higher rates mean for Anne Arundel County buyers and sellers?
Higher rates have slowed sales, but prices are still edging up. Maryland REALTORS' September 2026 numbers (Bright MLS data) for Anne Arundel County:
Anne Arundel County housing statistics, September 2026 vs. September 2025
Probably not by much. Freddie Mac's 30-year fixed average was 7.32% as of October 22, 2026, and October 2026 forecasts put the fourth-quarter 2026 average at 7.4% (Fannie Mae) and 7.3% (MBA).
Are mortgage rates expected to drop in 2027?
Only slightly, if at all. The MBA's October 2026 forecast shows the 30-year easing from 7.2% to 7.1% during 2027, while Fannie Mae's October 2026 forecast holds it at 7.5% for every quarter of 2027.
When will mortgage rates drop?
No one can name a date. The current forecasts show a slow decline at best, so watch the weekly Freddie Mac survey, inflation reports and each month's Fannie Mae and MBA forecast. We refresh this page monthly.
What is the best mortgage rate today?
Freddie Mac's weekly average was 7.32% for a 30-year fixed and 6.68% for a 15-year fixed as of October 22, 2026, for borrowers with strong credit and 20% down. Your best rate is the lowest same-day quote you receive after comparing Loan Estimates from more than one lender.
How much does a lower rate save on an Anne Arundel County home?
On a $402,400 loan (20% down on the county's $503,000 September 2026 median), principal and interest is about $2,764 a month at 7.32% and about $2,704 at 7.10%, a savings of about $60 a month.
Should I wait for rates to drop before buying near Fort Meade or Crofton?
Waiting is a bet on both rates and prices. Forecasts do not show a large drop soon, and Anne Arundel County's median price still rose 2.4% year over year in September 2026. Many buyers buy when the payment fits and refinance later if rates fall.
Talk to a local lender before you decide
Your rate depends on your credit, down payment, loan type and timing, so a national average is only a starting point. Call The Scott Smolen Team at 301-651-1261.
The Scott Smolen Team at RE/MAX Leading Edge, 1655 Crofton Blvd, Suite 203, Crofton, MD 21114.
Disclaimer: This article is general information, not financial, tax or legal advice, and it is not a loan offer or rate quote. Rates, forecasts and market data change often. Mortgage rates are Freddie Mac PMMS weekly averages as of October 22, 2026; Freddie Mac publishes new averages every Thursday. Payment examples are principal and interest only and are for illustration. Confirm terms, eligibility and costs with a licensed mortgage lender.
Sources:
Freddie Mac, Primary Mortgage Market Survey, U.S. weekly averages as of October 22, 2026: View official source (accessed October 22, 2026)
Freddie Mac, PMMS historical weekly rates since 1971 (CSV download): View official source (accessed October 22, 2026)
Fannie Mae Economic and Strategic Research, Housing Forecast: October 2026 (dated October 12, 2026): View official source (accessed October 19, 2026)
Mortgage Bankers Association, Mortgage Finance Forecast, October 11, 2026: View official source (accessed October 19, 2026)
Mortgage Bankers Association, MBA Newslink, Chart of the Week: Mortgage Originations Forecast (October 16, 2026): View official source (accessed October 19, 2026)
Maryland REALTORS, Housing Statistics: September 2026 (Bright MLS data): View official source (accessed October 19, 2026)
CFPB, How do mortgage lenders calculate monthly payments?: View official source (accessed October 19, 2026)
2026 Fort Meade BAH Rates: What They Mean for Renting or Buying Near Base
If you have orders to Fort George G. Meade, welcome to the neighborhood. One of the first questions we hear from military families is simple: "How far will our BAH go here?" This guide covers the 2026 Basic Allowance for Housing (BAH) rates for Fort Meade, which nearby ZIP codes share those rates, and how BAH fits with renting or buying a home, including with a VA loan.
Anne Arundel County Real Estate: October 16, 2026 IDX Snapshot
Countywide inventory spans a wide range of price points and communities. Separate property types first, then compare the homes that compete in your particular location and budget.
Crofton Real Estate: October 16, 2026 IDX Snapshot
Crofton’s current website inventory has more condos and townhouses than single-family homes. Buyers and sellers should compare their own segment rather than rely on one blended figure.