Scott Smolen Maryland real estate blog with market updates, community spotlights, and home buying tips

Maryland Real Estate Blog

Scott Smolen's Anne Arundel County and Bowie, Md. Real Estate Blog

Local real estate updates, market insights, community spotlights, and practical home buying and selling advice for Odenton, Gambrills, Crofton, Bowie, Piney Orchard, Two Rivers, and the surrounding Maryland real estate market.

Latest Market Trends

Stay current on mortgage rates, local inventory shifts, pricing trends, and buyer demand across the Maryland real estate market.

Home Selling Advice

Learn how to prepare, price, market, and negotiate when selling a home in today’s local market.

Home Buying Tips

Get practical guidance on affordability, inspections, offers, financing, and buying with confidence.

Community Spotlights

Explore local neighborhoods, market reports, lifestyle features, and community insights throughout the area.

May 9, 2024

What Are Some Ways to Utilize Your Tax Refund If You're Considering Buying a Home?

Are you saving up to buy a home this year? If so, you are likely aware of the various expenses involved, from the down payment to closing costs. However, did you know that your tax refund could assist with covering some of these costs? As explained by Credit Karma, if your goal is to transition from renting to homeownership, your tax refund can provide a helpful boost towards achieving that goal. While the amount of your tax refund may vary, it is helpful to have a general idea of what to expect. According to CNET, the average refund size has increased by 6.1% this year, which could be encouraging news.

If you receive a refund, there are several ways you can use it when purchasing a home, as outlined by Freddie Mac:

1. Saving for a down payment: Using your tax refund can help you make progress towards your down payment savings goal, which is often one of the biggest hurdles to homeownership.

2. Paying for closing costs: Your tax refund can also be directed towards covering the closing costs, which typically range from 2% to 5% of the home's purchase price.

3. Lowering your mortgage rate: Some lenders offer the option to buy down your mortgage rate, which can be beneficial if you are seeking a more affordable mortgage rate.

To prepare for buying a home, it is essential to collaborate with a team of trusted real estate professionals who can guide you through the process and help you understand what steps you need to take to be ready.

In conclusion, your tax refund can play a significant role in reaching your savings goal for buying a home. Consider reaching out to Scott and the Smolen Team to discuss your home buying aspirations and how they can assist you in achieving them. Your dream home may be more attainable than you realize.


May 7, 2024

Selling Your Parents’ Home After They Pass Away: Hiring a Real Estate Agent

Selling your parents’ home after their passing can be an emotional and complex process, especially when navigating the legal and financial aspects of an inherited property. One crucial step in this journey is hiring the right real estate agent. Selecting an agent that all heirs both like and trust is essential for a smooth and successful sale. Additionally, it's important to choose an agent with experience in handling probate or inherited property sales.

“When selling your parents’ house, you need an agent who has experience with transactions similar to your situation,” advises Ryan McKee, a California real estate agent and probate specialist. His expertise in selling probate homes underscores the importance of working with someone who understands the unique challenges involved.

Beyond experience, the right agent should demonstrate empathy and patience during this sensitive time. They should also be familiar with the local market where the property is located.

An out-of-state agent won’t have the necessary licensing to sell real estate in your parents’ home state, nor will they have access to local MLS data for accurate pricing and comparisons.

In addition to choosing the right agent, addressing the financial aspects of the property early on is crucial. Your agent can assist in uncovering any existing mortgage details, homeowner association fees, and other financial obligations associated with the property. This early preparation helps prevent surprises and ensures a smoother transaction process.

In Conclusion

Navigating the sale of an inherited home involves numerous considerations, from choosing a knowledgeable real estate agent to addressing financial details. By hiring an experienced and empathetic agent, you can streamline the process and reduce stress during this challenging time. Scott and the Smolen Team are here to guide you through each step, offering expertise in selling inherited properties and ensuring that every detail is handled with care. Contact Scott today to make the sale of your inherited home as smooth and straightforward as possible.


May 5, 2024

The Importance of a Realtor When Purchasing Your New Construction Home

The journey of buying a new construction home is an exhilarating one. The prospect of being the first owner and the ability to tailor your home's features to your liking offers numerous advantages. Yet, delving into the intricacies of purchasing a home still under construction can be overwhelming at times. This is where a proficient real estate agent steps in to make a significant impact.

An insightful article from The Mortgage Reports encapsulates the essence of this role:

"Your Realtor or real estate agent will be instrumental in guiding you through this process... they can provide you with direction during the construction phase and adeptly handle any potential hiccups that may arise."

Here's how your chosen agent serves as an invaluable asset in your quest to discover and acquire your new residence.

Local Expertise and Market Knowledge

Your real estate agent possesses an in-depth understanding of emerging neighborhoods and upcoming developments that could sway your decision. For instance, it's vital to be informed if there are plans to construct a highway near the wooded area behind your potential backyard. Evaluating how the community and its surroundings might evolve is crucial before finalizing your home purchase. Your agent aids in identifying a neighborhood that harmonizes perfectly with your preferences, lifestyle, and future aspirations.

Assessment of Construction Standards and Builder Reputation

Moreover, an agent boasts the acumen to evaluate the caliber of construction and the reputation of various builders. Their familiarity with local builders empowers them to provide insights into each one's track record, client satisfaction, and construction methodologies. Such insights steer you away from potential pitfalls and enable you to confidently opt for a builder recognized for delivering top-notch residences.

Guidance in Customization and Enhancements

The most apparent advantage of choosing a new home construction is the ability to tailor your dwelling to your exact specifications. Your agent becomes your guide throughout this process, offering advice on upgrades that are likely to enhance your home's long-term value. Their expertise ensures that your budget is allocated to areas that will yield the highest return on investment down the line.

Comprehension of Builder Contracts and Negotiations

Contracts with builders can be intricate and differ from conventional home purchase agreements. Your agent's role is to demystify these contracts and ensure you grasp the terms and conditions fully. Their adept negotiation skills also come into play, advocating on your behalf, and potentially securing improved deals, upgrades, or incentives as the process unfolds.

In Conclusion

The guidance and proficiency of a local real estate agent like Scott and the Smolen Team have the power to transform your dream of the perfect home into a tangible reality. Connecting with Scott, or an agent that he can connect you with if you are moving out of the area will grant you the confidence to embark on purchasing your new construction home.


May 1, 2024

Seize the Moment: Why Selling Your House Now is a Smart Move

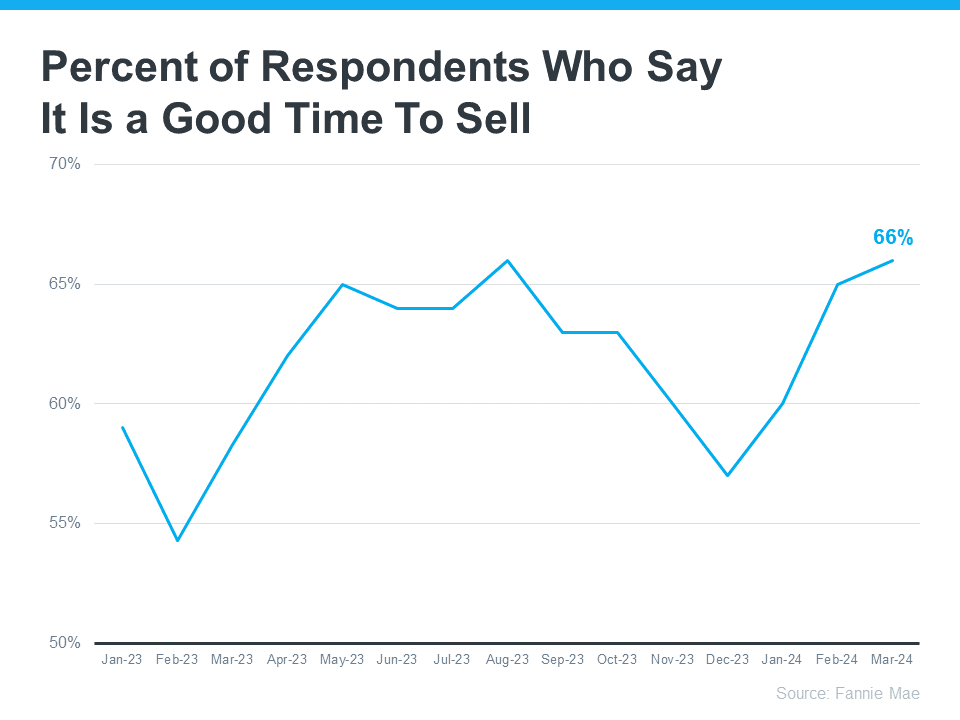
Considering selling your house? Alongside factors like mortgage rates and personal needs, there is another aspect worth pondering. The latest Home Purchase Sentiment Index (HPSI) from Fannie Mae reveals an uptick in the percentage of respondents who believe it is an opportune time to sell.

Why the surge in seller optimism?

Well, it is no secret that late spring and early summer traditionally mark the peak seasons for selling homes. As noted in a recent Bankrate article, these periods witness heightened buyer activity, driving up demand. Despite prevailing mortgage rates, the ongoing scarcity of inventory continues to empower sellers across most markets.

Rocket Mortgage reinforces this trend, highlighting that homes listed during this period tend to sell faster and at higher prices. This convergence of seasonal demand and limited supply presents a favorable landscape for sellers.

So, what does this mean for you?

As more sellers recognize the advantageous conditions, an increasing number are listing their homes for sale. If you are contemplating joining this wave, now's the time to start preparations. Enlisting the support of a local real estate agent can be invaluable in readying your home for sale. They offer tailored advice on enhancements to maximize appeal to buyers in your area. Moreover, they understand the dynamics of listing during peak seasons, potentially leading to swift sales and favorable prices.

In essence, seizing the spring and early summer market presents an opportunity to capitalize on the current seller's market. When you are ready to make the most of these conditions, reach out to Scott and the Smolen Team for expert guidance.


April 29, 2024

Real Estate Contingencies: A Guide for Home Buyers

If you're currently in the process of purchasing a home, you may have come across the term "contingency." Contingencies are crucial clauses in your contract that provide you with an option to back out if unforeseen issues arise between making an offer and the closing date. These contingencies safeguard your earnest money and can also give you leverage during negotiations with the seller.

What Exactly is a Real Estate Contingency?

A real estate contingency is a specific section in the purchase and sale contract that outlines conditions that must be met within a predetermined deadline for the deal to proceed successfully. If these conditions are not fulfilled, the buyer has the option to terminate the contract.

Real estate contingencies can be either "hard" or "soft." A hard contingency necessitates a physical sign-off, while a soft contingency automatically expires after a certain date. If a buyer needs to cancel the contract due to a contingency, the offer should clearly specify the method for notifying the seller, and a real estate agent or attorney can help navigate this legal process.

Understanding Contingent Offers

A contingent offer is when a buyer makes an offer to purchase a home but reserves the right to withdraw from the deal, with their full earnest money deposit, if the conditions outlined in the contingency clause are not met.

Pros and Cons of Contingent Offers

Utilizing a contingent offer offers several advantages to buyers. It safeguards the initial investment of earnest money, reduces the risk of purchasing a home with unforeseen issues, and protects against potential financial difficulties if the buyer is unable to secure a loan. Buyers can include real estate contingencies for a wide range of reasons, such as evaluating the functionality of home systems or the need for aesthetic repairs.

However, in competitive markets with multiple high-priced offers, sellers may prefer offers with fewer or no contingencies. According to the Zillow Group Consumer Housing Trends Report, 39% of buyers said they waived at least one contingency. Only sellers with limited options may accept offers with excessive contingencies. To remain competitive while protecting their interests, buyers should consult their agent for guidance on which contingencies to include in their offer.

Common Real Estate Contingencies

As you draft your purchase offer, a knowledgeable real estate agent like Scott will consider the property's market value, local competition, and strategies to appeal to the seller while safeguarding your investment with relevant contingencies.

Some contingencies are standard, such as those required by your lender, like the appraisal and financing contingencies. Here are some common real estate contingencies you may encounter while buying a home:

1. Disclosure Contingency: This contingency involves accepting the seller's disclosure form, which provides information about the property's condition and any known issues. You typically have a defined period to review the disclosure and decide whether to proceed with the transaction.

2. Inspection Contingency: This contingency allows you to conduct a professional home inspection and request repairs, or credits based on the findings. Waiving this contingency can be tempting in competitive markets, but it comes with potential risks.

3. Appraisal Contingency: For buyers using a mortgage, an appraisal contingency protects against overpaying for a property. If the appraisal comes back lower than the offer price, renegotiation or contract cancellation may be possible.

4. Financing Contingency: This standard contingency safeguards buyers in case their financing falls through, ensuring they won't be bound to purchase a home they can't afford.

5. Home Sale Contingency: If you need to sell your current home to afford the new one, this contingency allows you to back out if you can't sell your existing property.

6. Kick-Out Clause: Often added to offers with a home sale contingency, this clause allows the seller to continue marketing the home and accept a better offer within a specified timeframe.

7. Title Contingency: Ensures the seller has a clear title to transfer ownership to the buyer, with any issues resolved before closing.

8. Homeowners Insurance Contingency: Allows the buyer to obtain affordable insurance for the property.

9. Homeowners Association (HOA) Contingency: Allows buyers to back out if they are not comfortable with the HOA's requirements or restrictions.

Discuss Real Estate Contingencies with Your Agent

Working with an experienced real estate agent like Scott and the Smolen Team is crucial in navigating contingencies and protecting your interests during the home buying process. Discuss your concerns and deal breakers so that your needs are adequately addressed in your purchase contract. With the right guidance, you can proceed with confidence and make informed decisions throughout your home buying journey.


April 27, 2024

Understanding Building Permits for Home Improvements

When planning home improvements, it's easy to focus on design choices, paint colors, and the overall impact on property value. However, one critical consideration often overlooked is the need for a building permit. Understanding when a building permit is required can save you from potential legal and safety issues down the road. Let's delve into the world of building permits to ensure your home improvement projects are on the right track.

What is a Building Permit?

A building permit is an official document issued by the local government that authorizes construction on a particular project. These permits ensure that home improvements or remodeling adhere to essential safety standards, minimizing risks like structural collapse, fire hazards, and electrical accidents. Although obtaining a building permit might seem like a bureaucratic process, it serves to protect you, your family, and your investment.

Projects Requiring a Building Permit:

While regulations vary by city, generally, any work involving structural, electrical, plumbing, or mechanical changes will require a residential permit. Here is a breakdown of common home improvement projects that necessitate a building permit:

1. Fencing Installation or Repair: Check your city's regulations for fence height restrictions before installing or repairing a fence. Ensure your fencing contractor is aware of these restrictions to avoid future issues.

2. Window Installations: Installing larger windows, skylights, or doors with windows will likely require a permit to create necessary openings. It is advisable to enlist the help of a professional window installer who can handle the permits.

3. Plumbing and Electrical Work: Replacing or installing plumbing fixtures, electrical wiring, outlets, switches, fans, or lighting usually requires a permit. Smaller projects like repairs and light fixture installations may not need a permit.

4. Structural Changes: Any modifications to load-bearing walls, balconies, decks, porches, roofs, or foundations will need a permit.

5. Heating Maintenance: Replacing water heaters, making changes to ventilation systems, gas or wood fireplaces, and ducts will require permits.

6. Additions and Remodels: If your project involves additions, remodels, repairs, replacements, or upgrades exceeding $5,000, a permit is necessary. Some exceptions include construction under 200 square feet, painting, carpeting, and wallpapering.

Projects Exempt from Permits:

Certain home improvement projects can be done without a permit, including minor plumbing and electrical work, painting, wallpapering, flooring installations (hardwood, carpeting, linoleum, or vinyl tile), installing countertops, and landscaping. However, keep in mind that regulations can differ from one area to another, so contacting your local building office for clarity is wise.

Obtaining a Building Permit: When working with a contractor, they will often handle obtaining the permit as they are responsible for ensuring the project meets code requirements. If you decide to pull the permit yourself, you assume the role of the contractor in the eyes of your local government and become liable for compliance.

Consequences of Ignoring a Building Permit:

Skipping the permit process may seem like a time and cost-saving measure, but it can lead to severe repercussions:

1. Fines and Penalties: Code enforcement authorities can impose fines far exceeding the original permit cost if they discover unpermitted work. They may also require you to redo the project.

2. Home Sale Delays: Unpermitted work can be uncovered during a home inspection when selling your house, causing delays, or even necessitating undoing the previous work.

3. Insurance Issues: If an incident like a plumbing problem, fire, or structural collapse is linked to unpermitted work, your homeowners' insurance may not cover the damage. Don't overlook the importance of building permits! While they may seem like a hassle, obtaining a permit is crucial for your safety and the protection of your home.

Taking the time and spending a little extra money upfront can save you from potential costly and stressful consequences down the line. Prioritize safety and compliance by getting a building permit for your home improvement projects.


April 25, 2024

The Hazards of Selling Your House Without a Realtor

Are you contemplating the sale of your home as a For Sale by Owner (FSBO)? Before you take the plunge, it's crucial to acknowledge that the process demands far more time and expertise than you might initially assume. Although the notion of handling it solo may be enticing, it's essential to grasp the challenges you may encounter. As recently highlighted in a Bankrate article:

"Selecting the right asking price, composing an appealing listing, reaching out to potential buyers, arranging showings, and handling paperwork—these are all tasks that you will need to tackle yourself in the absence of a real estate agent."

Here is a closer look at some of these aspects and the potential downsides of proceeding without an agent.

Pricing Pitfalls

Setting the correct price for your property is pivotal to achieving a successful sale. Real estate agents possess the expertise needed to navigate the current housing market and determine the ideal pricing strategy to attract potential buyers. Unfortunately, homeowners who opt to go solo often lack this vital experience. This can result in one of two common pitfalls: overpricing or underpricing the property.

Nerd Wallet offers the following advice: "If your home is overpriced, you run the risk of prospective buyers not even noticing the listing. . . . Conversely, pricing your home too low might leave money on the table and raise suspicions about underlying issues with the property."

To steer clear of these pitfalls, it is prudent to collaborate with a real estate agent who can ensure your property is priced at its current market value, positioning it to make a compelling first impression.

Limited Marketing Expertise

In this digital era, online marketing has become a game-changer, particularly in the realm of property sales. A recent report from the National Association of Realtors (NAR) underscores this fact: "Among all generations of homebuyers, the initial step in the home search process is to explore properties online."

By partnering with a real estate agent well-versed in leveraging online marketing tools and resources, you can increase your exposure to tech-savvy house hunters, significantly enhancing your chances of a successful sale. However, if you decide to sell your property independently, you might miss out on the full potential of online and social media marketing strategies.

Navigating Negotiations

Selling your home is not solely about finding a buyer; it also involves a complex web of negotiations. You'll need to interact with various parties, including the buyer, the buyer's agent, the inspection company, the appraiser, and more. It's a delicate dance where every move matters, and the expertise of a real estate agent can be invaluable in steering negotiations and sealing the deal.

As NerdWallet aptly points out: "Your listing agent will stand by your side during negotiations, double-checking paperwork, liaising with the buyer's agent and other involved parties, and overseeing the process until the closing date."

In Conclusion

If you are contemplating the sale of your property, and the thought of going solo has crossed your mind, take a moment to ponder your decision carefully. Reach out to Scott and the Smolen Team today to explore how their experience can alleviate the stress associated with this significant transaction.


April 23, 2024

Determining Your Ideal Home Budget: 5 Tips for Informed Decision-Making

So, you have made the exciting decision to purchase a new home. But now comes the crucial question: How much can you truly afford? To guide you through this pivotal step and simplify the process, we have outlined five invaluable tips to assist you in determining your optimal home budget.

1. Grasp the Percentage Allocation to Your Mortgage

The first step in understanding your home budget is to calculate the proportion of your income that should be directed towards your mortgage. Start by tallying your total gross annual income, encompassing earnings from all sources such as salary, wages, tips, and commissions. If you have a partner contributing to the household income, ensure you include their earnings as well. Divide this sum by 12 to derive your monthly income, which forms the foundation for your mortgage calculations.

Now, it's time to adhere to the widely recognized 28/36 rule. According to this rule, your housing expenses should not surpass 28% of your monthly income, and your total debt, including your mortgage, should not exceed 36%. Sticking to these parameters ensures that you retain sufficient funds for essentials like groceries, fuel, vacations, and future savings. For instance, let's say you and your spouse are eyeing a house in Anaheim with a combined monthly income of $6,000. Applying the 28/36 rule, you would not want to allocate more than $1,680 towards housing expenses (28% of $6,000) and $2,160 for total debt (36% of $6,000).

2. Employ an Affordability Calculator

Utilizing a home affordability calculator is a smart move to gauge the kind of house you can comfortably afford. By inputting essential information such as your location, annual income, savings for a down payment, and current monthly expenses, this calculator provides a clear picture of your potential home budget.

For precision, you can further refine your calculations by adding advanced filters like monthly homeowners' insurance, mortgage interest rate, private mortgage insurance (if applicable), loan type, and the property tax rate. The more details you include, the closer you will get to determining your ideal home budget.

3. Acknowledge the Influence of Mortgage Rates

Mortgage interest rates play a pivotal role in shaping your home-buying affordability. These rates represent the cost levied by lenders for providing you with a home loan. Expressed as a yearly percentage of the total loan amount, they significantly impact your monthly mortgage payment. Even a minor difference in the interest rate, such as a single basis point (one-hundredth of a percentage point), can be the distinction between a home being within your budget or beyond it. Be sure to explore multiple lenders and seek the most favorable rate available.

4. Account for Additional Homebuying Expenses Purchasing a home involves more than just the purchase price. Here are common costs you should factor in:

a. Down Payment: The initial significant expense is your down payment. This is the cash you contribute towards the home's purchase price. Different loan options stipulate down payment requirements ranging from 3% to 20% of the home's purchase price. If your down payment is less than 20%, you may also be required to pay for private mortgage insurance (PMI). This insurance safeguards the lender in the event of default on mortgage payments and typically ranges between 0.5% and 1% of your annual mortgage, added to your monthly payment.

b. Closing Costs: Closing costs include lender and escrow fees, insurance, and taxes necessary to finalize the home purchase legally. These expenses typically amount to 3-6% of the home's total purchase price. For example, if you're buying a $500,000 home in Austin, you should anticipate spending approximately $15,000 to $30,000 on closing costs, payable when closing on the home.

5. Prepare for Ongoing Homeownership Expenses

Your responsibilities as a homeowner continue well beyond the closing day. Be sure to allocate funds in your budget to cover your monthly home expenses and set aside money for future repairs and upgrades.

a. Utilities: Owning a home may introduce you to new expenses like utilities, which were previously covered by your landlord. Be prepared to manage sewer, water, garbage, internet, cable TV, natural gas, and electricity costs on top of your mortgage.

b. Property Taxes and Insurance: While you'll address an initial portion of property taxes and homeowners insurance at closing, remember that these payments continue as long as you own the home. Costs may fluctuate based on your home's value, location, and annual adjustments.

c. Home Maintenance and Repairs: As a homeowner, you are responsible for addressing breakdowns and damages, be it a malfunctioning appliance, plumbing issue, or home damage from unforeseen events. Additionally, allocate funds for routine maintenance tasks like gutter cleaning, carpet care, and deck maintenance. Consult a home maintenance checklist for a comprehensive guide.

In Conclusion

Determining your ideal home budget is a personalized process influenced by numerous factors. Familiarizing yourself with these essential costs will help you make an informed decision and potentially save you money on your home purchase. Reach out to Scott and the Smolen Team today to initiate the first steps toward owning your new home and gain access to valuable mortgage resources!
 

April 21, 2024

Selling Your Parents’ Home After They Pass Away: Address Inheritance Disagreements Before They Escalate

Handling the sale of a deceased parent’s home can be a complex and emotional process, particularly when multiple heirs are involved. It’s crucial to address potential points of conflict early on to avoid costly and stressful disputes later. Open communication and clear agreements can prevent minor disagreements from becoming major disputes.

Key Areas to Address Early

1. Assign Responsibilities: Determine who will handle the preparation of the house for sale. This includes cleaning, repairs, and any necessary renovations. Clearly define each heir's responsibilities to avoid confusion and ensure the property is presented in the best possible condition.

2. Covering Sale Expenses: Decide who will be responsible for funding the costs associated with selling the home. This includes real estate agent fees, repairs, and any other related expenses. Agree on whether these costs will be covered by the estate or paid out of pocket by the heirs.

3. Splitting the Proceeds: Agree on how the proceeds from the sale will be divided among the heirs. While equal distribution is common, it’s important to consider any special circumstances or contributions made by individual heirs. Document the agreed-upon division to avoid future disputes.

4. Valuing the Property: Agree on how to determine the home's value. This could involve hiring a professional appraiser or real estate agent to provide an unbiased valuation. Establishing a fair market value is crucial for making informed decisions and ensuring an equitable distribution of proceeds.

5. Decision-Making Authority: Determine who will have the final say on accepting offers. This could be the appointed executor, a majority vote among heirs, or another agreed-upon method. Clarify this process in advance to prevent delays and conflicts during negotiations.

Seek Professional Mediation if Needed

If disagreements arise that cannot be resolved through discussion, consider enlisting the help of a professional mediator. Mediators specialize in facilitating negotiations and helping parties reach a consensus. They can provide valuable guidance and ensure that all voices are heard, which can be especially helpful in emotionally charged situations.

In Conclusion

Navigating the sale of a parent’s home after their passing can be particularly challenging, especially with multiple heirs involved and differing opinions. By addressing potential conflicts early and establishing clear agreements, you can streamline the process and reduce stress. Open communication and, if needed, professional mediation can help ensure the sale proceeds smoothly and fairly for all parties involved. These steps will not only facilitate an efficient sale but also help maintain family harmony during a difficult time. For expert guidance and support throughout this process, contact Scott and the Smolen Team. Their experience and dedication can make a significant difference in managing the sale of your inherited property.


April 19, 2024

Navigating Long-Distance Moves: A Stress-Free and Efficient Transition

Whether you are venturing to a fresh abode in Seattle, or setting roots in a Houston townhouse, embarking on a journey to a new city or state brings excitement and change. Yet, the intricacies of long-distance relocation can also evoke overwhelming feelings. The key to success lies in meticulous planning and organization. In this comprehensive guide, discover ten invaluable insights from Scott to streamline your long-distance move, minimizing stress and maximizing efficiency.

1. Commence Planning Early

Long-distance moves thrive on foresight. Commence the process well in advance, ideally 8 to 12 weeks before your target move date. Craft a comprehensive checklist and timeline, encompassing pivotal tasks. Research moving companies, sort belongings, declutter, and arrange essential services like utility transfers. Do not overlook the need for an adequate number of moving boxes.

2. Enlist a Reputable Moving Company

The choice of a moving company is pivotal. Delve into research, scrutinizing reviews to gauge reputation and client contentment. Collect written estimates from multiple movers, comparing services and pricing. Prioritize licensed, insured companies with a strong history of managing long-distance moves.

3. Streamline Possessions

Trimming unnecessary belongings proves cost-effective during long-distance moves. Seize the opportunity to declutter rigorously. Sell, donate, or discard items not in use. Consider garage sales or online selling to offset moving expenses. Reducing the load not only saves money but simplifies packing and unpacking.

4. Secure Important Documents

Guard vital documents from misplacement. Organize passports, IDs, birth certificates, medical records, financial paperwork, and housing contracts. Maintain accessibility to these documents, carrying them personally rather than packing them.

5. Adopt a Methodical Packing Approach

Organize packing room by room, proceeding from infrequent to daily-use items. Employ quality packing materials—sturdy boxes, bubble wrap, packing paper, and durable tape—for safeguarding belongings. Individually wrap fragile items. Label boxes with contents and corresponding rooms, easing unpacking and room placement.

6. Maintain an Inventory

Craft an exhaustive inventory pre-move. Particularly crucial for long-distance journeys, where belongings co-mingle. Tracking possessions ensures safe, comprehensive delivery. The inventory aids insurance claims in case of mishaps.

7. Strategize Travel and Accommodation

Pre-plan routes, accommodations, and travel times if driving. Book flights ahead for air travel. Arrange transportation from airports to new homes. Plan for pets' comfort during travel.

8. Notify Pertinent Parties

Alert utility providers, banks, insurers, credit card companies, and governmental agencies of address changes. Inform subscriptions, acquaintances, and family for uninterrupted mail flow.

9. Pack an Essentials Box

Assemble an essentials box with immediate-needs items. Toiletries, clothing, vital documents, basic kitchen supplies, and essential tools should reside in this box. Keep it separate from main belongings for swift access.

10. Embrace Positivity and Flexibility

Accept that challenges may arise. Maintain a positive attitude and flexibility, embracing the adventure and new prospects awaiting in your new home. In the midst of the whirlwind excitement and change that comes with embarking on a long-distance move, meticulous planning and organization are your strongest allies.

By following the invaluable insights shared in this comprehensive guide, courtesy of Scott and the Smolen Team, you can streamline your relocation process, minimize stress, and maximize efficiency. From commencing planning early to embracing positivity and flexibility, each step is designed to ensure a smooth transition as you set forth on your journey to a new city or state! With foresight and preparation, you can confidently navigate the intricacies of long-distance relocation, turning challenges into opportunities for growth and new beginnings.