Scott Smolen Maryland real estate blog with market updates, community spotlights, and home buying tips

Maryland Real Estate Blog

Scott Smolen's Anne Arundel County and Bowie, Md. Real Estate Blog

Local real estate updates, market insights, community spotlights, and practical home buying and selling advice for Odenton, Gambrills, Crofton, Bowie, Piney Orchard, Two Rivers, and the surrounding Maryland real estate market.

Latest Market Trends

Stay current on mortgage rates, local inventory shifts, pricing trends, and buyer demand across the Maryland real estate market.

Home Selling Advice

Learn how to prepare, price, market, and negotiate when selling a home in today’s local market.

Home Buying Tips

Get practical guidance on affordability, inspections, offers, financing, and buying with confidence.

Community Spotlights

Explore local neighborhoods, market reports, lifestyle features, and community insights throughout the area.

May 6, 2023

Housing News and Economic Updates - Purchase Mortgage Applications Down, Refinance Mortgage Applications Up Slightly

Housing News:

Purchase mortgage applications dropped 2% last week and were down 32% from a year ago. Tight inventory continues to hamper sales.  We do not see this trend changing in our area until more homeowners decide to sell their current homes.  Since many homeowners were able to buy, or refinance into historically low interest rates they are tending to stay in their current home, or use them as rental property instead of selling.  Homes that are prepared correctly, priced accurately, and marketed aggressively are still often seeing multiple offers.   

Mortgage applications to refinance were up 1% on the week, despite being down 51% from the year before. Overall construction spending was up in March, although single-family homebuilding remained depressed amid higher mortgage rates.  Another avenue to reverse the low housing inventory is for new construction to increase.  However that has not been the case in this area for a variety of reasons.    

Economic News:

The Fed raised its policy rate by 0.25% this week. This 10th consecutive hike puts the rate above 5% for the first time since 2007.  Job openings fell more than expected in March to the lowest level in nearly two years, a sign the job market is loosening. Applications for unemployment benefits also rose by the most in six weeks, while continuing claims fell by the most since July. 

The Federal Reserve remains the most influential entity in the mortgage market, with the power to determine mortgage rates according to their objectives. They recently voted to instruct the Open Market Desk at the Federal Reserve Bank of New York to carry out transactions in the System Open Market Account. The market experienced some instability due to the FDIC's bailout of another regional bank.

Weekly jobless claims were slightly higher than expected at 242K versus 240K, but unemployment fell to 3.4% from 3.6%. Payrolls exceeded predictions at 253K versus 180K. 

Mortgage interest rates remained basically unchanged for the week. On Friday, May 05, 2023, the national average 30-year fixed mortgage APR is 6.80%. The average 15-year fixed mortgage APR is 6.18%, according to Bankrate's latest survey of the nation's largest mortgage lenders.

May 5, 2023

Get a Fresh Look for Your Kitchen Cabinets Without Breaking the Bank

If you're tired of the appearance of your kitchen cabinets, but don't want to spend a fortune on a full renovation, painting or refacing might be the solution you're looking for. Here are some options to consider, along with the advantages and disadvantages of each. Let’s take a closer look together.

The pros of painting cabinets

Painting your cabinet doors can save you a lot of money in the long haul. Although it'll take some effort, the cost of paint and supplies will be a fraction of what you'd spend on new doors. If your present doors are still in decent condition, painting them is a fantastic alternative.

The cons of painting cabinets

While painting cabinet doors can give your kitchen a fresh new look, it's important to keep in mind a few potential drawbacks. One thing to be aware of is that some people may experience more sticking when opening cabinets after the doors have been painted. Additionally, areas with more physical contact, such as near door pulls and knobs, may experience paint rubbing off.

Tips for painting cabinet doors

If durability is a top priority, opt for oil-based paint instead of latex paint for high-use cabinets. Although, keep in mind that painted cabinets will require time to dry. But trust us, the results will be well worth it. Different types of cabinets require different types of paints. For example, wood, laminate, and metal cabinets each have unique properties that need to be taken into consideration. Laminate cabinets, for instance, will need a special bonding primer treatment before the topcoat of paint is applied. If you're planning to tackle the project on your own, make sure to clean the doors thoroughly with a degreasing spray and sand them before getting started. With the right paint and proper preparation, your cabinets will look brand new in no time!

The pros of replacing cabinet doors

If you're considering replacing your cabinet doors, there are two options: hiring a professional company or purchasing the appropriate size doors online. If you opt for a company, they'll be responsible for installing your new cabinet doors, simplifying the process for you.

The cons of replacing cabinet doors

Replacing cabinet doors can give your kitchen a brand-new look, but the price can be a deterrent. The good news? You can now easily buy cabinet doors online from trusted kitchen stores. Keep in mind that these doors usually come unfinished, so painting or staining will be required before installation. However, if your current doors are in poor condition, replacing them is a great option.

May 4, 2023

Demystifying Private Mortgage Insurance (PMI): Understanding the Basics

Introduction

When it comes to purchasing a home, many aspiring homeowners find themselves facing a common hurdle: the need for Private Mortgage Insurance (PMI). PMI is a type of insurance that protects lenders in case borrowers’ default on their mortgage payments. While PMI may add an additional cost to your monthly mortgage payment, it can also open doors to homeownership that would otherwise be closed. In this blog post, we will delve into the fundamentals of PMI, its benefits, drawbacks, and tips to potentially avoid it altogether.

What is Private Mortgage Insurance (PMI)?

Private Mortgage Insurance, commonly referred to as PMI, is a type of insurance policy designed to safeguard lenders against the risk of borrowers defaulting on their mortgage loans. It is typically required for homebuyers who make a down payment of less than 20% of the home's purchase price. In essence, PMI serves as a protection mechanism for lenders by reducing their financial exposure in case borrowers fail to make their mortgage payments.

How does PMI work?

PMI functions as an additional cost that is added to the borrower's monthly mortgage payment. The exact amount of PMI varies depending on factors such as the loan amount, down payment percentage, and the borrower's creditworthiness. The insurance premium is typically a small percentage of the total loan amount and is either paid monthly, as part of the mortgage payment, or as a lump sum upfront.

It is important to note that PMI benefits the lender, not the borrower. The insurance coverage reimburses the lender for a portion of the outstanding loan balance if the borrower defaults on their mortgage. This protection encourages lenders to offer loans with lower down payment requirements, making homeownership more accessible to individuals who may not have saved a substantial down payment.

Benefits of PMI

  1. Increased Access to Homeownership: PMI enables borrowers to purchase a home with a down payment of less than 20%. Without PMI, many individuals would struggle to enter the housing market due to the high upfront costs associated with a sizable down payment.
  2. Quicker Path to Equity: By utilizing PMI, homeowners can begin building equity in their homes sooner. They can enter the housing market earlier and potentially benefit from property value appreciation.
  3. Flexibility in Financial Planning: PMI allows borrowers to conserve their savings and allocate funds towards other financial priorities, such as home improvements, debt repayment, or emergency funds.

Drawbacks of PMI

  1. Additional Monthly Expense: PMI increases the borrower's monthly mortgage payment, adding to the overall housing costs. It is crucial for homebuyers to factor this expense into their budget to ensure affordability.
  2. No Direct Benefit to the Borrower: Unlike traditional insurance policies that protect the policyholder, PMI solely benefits the lender. Borrowers should be aware that they are paying for insurance coverage that offers them no direct protection or financial benefit.
  3. Difficult to Cancel: In the past, canceling PMI often required borrowers to refinance their mortgage or reach a predetermined loan-to-value ratio (LTV). However, recent changes in regulations have made it easier for borrowers to request the removal of PMI once their equity reaches a certain threshold. It is important for borrowers to understand the specific guidelines and requirements of their PMI policy.

Avoiding PMI

While PMI may be a necessary cost for many homebuyers, some strategies can help avoid it altogether:

  1. Save for a Larger Down Payment: By saving diligently and aiming for a down payment of at least 20%, borrowers can sidestep the need for PMI.
  2. Explore Lender-Paid Mortgage Insurance (LPMI): LPMI is an alternative option where the lender pays for the mortgage

Posted in
May 3, 2023

JPMorgan Chase to acquire troubled First Republic Bank, avoiding FDIC emergency powers

According to the Federal Deposit Insurance Corporation (FDIC), First Republic Bank has become the third major US bank to fail in recent months. In response, JPMorgan Chase will be taking over “all of the deposits and substantially all of the assets” of the troubled bank.

The FDIC noted that JPMorgan Chase’s acquisition of First Republic Bank’s assets will avoid the need for the agency to use its emergency powers and reduce disruptions for customers.

As of April 13, 2023, First Republic Bank held approximately $229.1 billion in total assets and $103.9 billion in total deposits. After the deal is finalized, all the bank's depositors will become depositors of JPMorgan Chase Bank, National Association and will have full access to their funds.

The collapse of Silicon Valley Bank and Signature Bank in recent months raised concerns of a wider banking crisis that could impact the global economy. However, the FDIC's announcement aims to ease these concerns by stating that JPMorgan Chase’s acquisition of First Republic Bank’s assets will avoid a potential takeover by the agency and minimize disruptions for loan customers.

“We were able to deal with First Republic’s failure without using the FDIC’s emergency powers. It is a grave and unfortunate event when the FDIC uses these emergency powers,” said FDIC Board of Directors member, Jonathan McKernan. “Any decision to use the FDIC’s emergency powers should be approached skeptically, taking into account the unique facts and circumstances of the time, and with careful attention to the implications for the future.”

Posted in
May 2, 2023

Understanding Real Estate Appreciation: Definition, Factors, and Importance

Real estate appreciation is a term that is commonly used in the world of real estate, but not everyone understands its meaning. In simple terms, real estate appreciation refers to an increase in the value of a property over time. This increase in value can occur due to various reasons, including economic growth, demand-supply dynamics, and the property's physical condition.

Real estate appreciation is an important concept for property owners, investors, and buyers to understand. Property owners can benefit from appreciation by selling their property at a higher price than they purchased it for, or by using it as collateral for loans or refinancing. Investors can benefit from appreciation by earning a return on their investment through rental income and by selling the property at a higher price in the future. Buyers can benefit from appreciation by purchasing a property at a lower price and then selling it at a higher price later.

Real estate appreciation is not guaranteed and is subject to various factors that can influence the value of the property. For example, changes in interest rates can affect the demand for property, which in turn can impact the property's value. Economic factors such as inflation, unemployment rates, and GDP growth can also have an impact on real estate appreciation.

Location is one of the most critical factors that can influence real estate appreciation. Properties located in desirable areas with good schools, amenities, and infrastructure tend to appreciate faster than those in less desirable locations. This is because there is a higher demand for properties in such areas, and supply may be limited. Other factors that can impact real estate appreciation include property size, age, condition, and features.

Real estate appreciation is not the same as cash flow, which is the income generated from a property through rental income or other sources. A property can appreciate but still have negative cash flow if the expenses associated with owning and managing the property exceed the income generated. Real estate appreciation is the increase in a property's value over time. It's a crucial concept for property owners, investors, and buyers alike to grasp. However, appreciation is reliant on several variables, such as location, economic conditions, and property attributes that influence a property's worth. While appreciation isn't guaranteed, it can have a considerable impact on the long-term profitability of a real estate investment.

Posted in
May 1, 2023

Maximizing Your Home's Storage Space: Creative Solutions for Your House

Storage space is one of the most important factors to consider when it comes to home organization. Whether you have a small apartment or a large house, having adequate storage is crucial to keeping your living space tidy and functional. Here are some creative storage solutions for every room in your home.

1. The Kitchen

The kitchen is often one of the busiest rooms in the house, and it's also one of the most challenging when it comes to storage. Here are some ideas to help you maximize your kitchen storage space:

  • Install pull-out shelves in your cabinets to make it easier to access pots, pans, and other kitchen items.
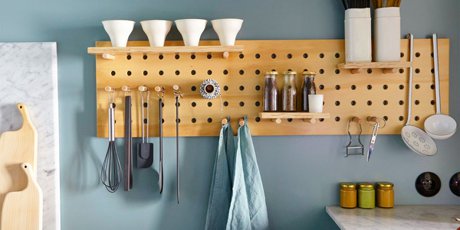
  • Hang a pegboard on the wall to keep utensils and other small items organized and within easy reach.
  • Use tension rods to create additional storage space under your sink for cleaning supplies.

2. Bedrooms

Bedrooms are a place where you want to feel relaxed and peaceful, so having clutter and messes can be stressful. Here are some tips to help you keep your bedroom organized:

  • Use under-bed storage containers to store seasonal clothing, extra linens, and other items that you don't use on a regular basis.
  • Install floating shelves on the wall to display books, photos, and decorative items while keeping surfaces clear.
  • Use a hanging shoe organizer to store small items like jewelry, socks, and undergarments.

3. The Living Room

The living room is often the central gathering place in a home, so it's important to keep it tidy and clutter-free. Here are some ideas for organizing your living room:

  • Use decorative baskets or bins to store throw blankets, magazines, and other items that tend to accumulate in the living room.
  • Install shelves or a built-in storage unit to display books, movies, and other items while keeping them organized.
  • Use a coffee table with built-in storage to keep remote controls, magazines, and other small items within easy reach.

4. Bathrooms

The bathrooms are other rooms where storage can be a challenge, especially in smaller spaces. Here are some tips for maximizing your bathroom storage space:

  • Use a over-the-toilet storage unit to add extra shelving and storage space without taking up floor space.
  • Install a medicine cabinet with built-in shelves and compartments to keep toiletries and medications organized and out of sight.
  • Use a shower caddy or hanging storage unit to keep shampoo, soap, and other shower essentials within easy reach.

By implementing these creative storage solutions in your home, you'll be able to maximize your space and keep your living areas organized and clutter-free.

Posted in
April 30, 2023

Home Listings Decrease Nationwide as Homeowners Opt to Stay Put

During the four weeks ending April 23, the number of newly listed homes for sale nationwide decreased by 22.4% compared to the previous year, representing one of the largest declines since the beginning of the pandemic. Homeowners are choosing to stay put in their current homes to retain their low mortgage rates, which have been increasing for the second consecutive week, and because they are facing challenges in finding another suitable property to purchase.

This shortage of new listings is causing an unexpected reduction in the overall number of homes available for purchase. The insufficient inventory is also contributing to a quicker selling time for some properties, with almost half of homes being sold within two weeks. This percentage is the highest it has been in nearly a year and has risen progressively throughout April, which is unusual for this time of year. Despite elevated mortgage rates deterring some buyers, pending home sales have declined by 17% year over year.

Recent data indicates the state of homebuying activity. During the week ending April 27, the average 30-year fixed mortgage rates increased slightly to 6.43%, marking the second consecutive week of a small rise after five weeks of declines. On April 27, the daily average rate was 6.67%.

In the week ending April 21, mortgage-purchase applications rose 5% from the previous week after being seasonally adjusted, but fell 28% from the same period the previous year.

During the week ending April 23, Google searches for "homes for sale" declined by around 8% from the previous month during the week ending April 22, and dropped about 20% compared to the same period the previous year.  According to ShowingTime, a home tour technology firm, touring activity as of April 22 rose about 28% from the beginning of the year, which is higher than the 17% increase observed at the same time last year.

If you have a home that you need to sell or one you are considering selling, it is still a great time to put it on the market.  We are still seeing many homes receive multiple offers.  Most homes are selling at, or above asking price with very few seller concessions in the Fort Meade area.  Even though mortgage rates have edged up into the 6's, they are still historically low, so Buyers are looking for nice homes that are priced correctly.   

Posted in
April 29, 2023

Mortgage Changes Explained - Clearing up LLPAs and Their Impact on Credit Scores

Headline Confusion: Mortgage Changes Explained

The new information about mortgage pricing is confusing to experts in the field, let alone the public.  I personally do not agree with what Fannie Mae and Freddie Mac are doing.  I do not think it is in the best interest of the housing market to confuse the public.  However this blog will explain how they are calculating everything and hopefully it will eliminate some the confusion that currently exists.

Recent changes to mortgage costs are not punishing those with higher credit scores. In fact, nobody with better credit will be paying more for a mortgage than somebody with lower credit. Let's dive into the facts and clear up any misinformation.

  • Loan Level Price Adjustments (LLPAs) are rate adjusters that are based on loan features including credit score and loan-to-value ratio. Throughout the years, Fannie Mae and Freddie Mac have made a number of changes to LLPAs. Recently, they have imposed new changes. Stay informed on what these changes mean for you.
  • While the change we are currently discussing may not be new news, we want to remind everyone that it went into effect on May 1, 2023, for loans delivered to Fannie/Freddie. Changes that impact fees and guidelines are almost always implemented based on the delivery date, so lenders have already priced in the change weeks ago.

Breaking News: The Truth About the "New" Mortgage Tax

You may have heard rumors of a new tax on mortgage borrowers with higher credit scores, but before you start panicking, let's get the facts straight. Contrary to popular belief, intentionally lowering your credit score won't give you a better deal on a mortgage rate. Don't believe those misleading headlines that suggest otherwise.

The truth is, changes to Loan Level Price Adjustments (LLPAs) imposed by Fannie Mae and Freddie Mac have caused some confusion. These adjustments are based on loan features such as your credit score and the loan-to-value ratio. While there have been changes to the LLPAs over the years, a substantial change was announced in January of this year. So, what does it all mean? Let us help you navigate through the noise and get the real story on this so-called "new" mortgage tax.

If this is news from January, why is everyone talking about it now?

Many people are confused about how "delivery dates" work for Fannie Mae and Freddie Mac loans. Essentially, changes that impact fees and guidelines are often implemented based on the date the loan is delivered to Fannie/Freddie. It's important to note that "delivery" typically occurs a few weeks after the loan has closed, but it can take even longer than that.

To add to the confusion, loans are often quoted and locked in for more than three weeks before delivery. This means that many lenders have already begun implementing changes that will go into effect on loans delivered on or after May 1st, 2023. In fact, some lenders have been implementing these changes for months, especially for loans with longer lock-in periods.

If you're a borrower or a lender involved with Fannie Mae or Freddie Mac loans, it's important to understand the delivery process and how it affects changes to fees and guidelines.

Are borrowers with lower credit scores receiving discounts, while those with higher credit scores are paying more?

Confused about LLPAs and their impact on credit scores? Let us clear things up for you. LLPAs are changing and these changes can result in lower costs for individuals with lower credit scores. However, those with higher credit scores may experience an increase in costs. It's important to note that this information is purely factual and does not offer any opinions on whether these changes are good or bad. Don't confuse the change with the actual cost.

The following tables show the differences in LLPAs before and after the change. RED = rising costs GREEN = falling costs

Looking at the initial chart, it may seem like those with a 640-credit score pay less than those with a 740. However, this is simply due to recent changes in the system.

To gain a more transparent understanding, we've provided a new table below which outlines the outright LLPAs for the same credit score and loan-to-value ratio matrix.  By understanding the impact of your credit score and loan-to-value ratio on your mortgage payments, you can make informed decisions and potentially save money in the long run.


Having a credit score of 640 versus 740 could cost you over $4000 on a $300k mortgage. That's right! Our example loan-to-value ratio of 80% means your loan level price adjustment (LLPA) at a 640 score is a whopping 2.25%, whereas a 740 score will only cost you 0.875%. That's a difference of 1.375% - almost half of what it used to be!

Are you wondering why the government is implementing a significant change that seems to affect people with higher credit?  Fannie Mae and Freddie Mac have a "mission" to promote affordable home ownership - this is according to their regulator, the Federal Housing Finance Agency (FHFA). While the change may seem sudden or unexpected, it is intended to align with that mission and ultimately make it easier for more Americans to buy homes.  Although these programs sound very magnanimous, these type of changes have resulted in major housing issues in the past, hopefully this will not lead to a repeat of what we saw in 2007.  The only thing we can do is learn about them and try to adopt them in to the system as smoothly as possible at this point.  

Here is the statement from the Federal Housing Finance Agency: Government Statement
Posted in
April 28, 2023

Simple Tips for Making Your Home Eco-Friendly

One of the easiest ways to go green is by making your home eco-friendlier! With a few small changes, you can have an environmentally conscious space that provides comfort and peace. Plus, living in such a house means you’ll be helping make a real difference for our planet—and it doesn’t take much effort either! Check out these simple tips to get started on creating an earth-loving abode today.

Pursue Energy Star Options:

Want to save money on your electricity bills, plus become a more eco-conscious household? Consider upgrading outdated appliances or electronics with Energy Star models! These energy-efficient devices provide long term cost savings and don't require any compromise in terms of lifestyle. For example, replacing traditional light bulbs with LED lights that are certified by the ENERGY STAR program could result in lifetime savings from $30 to $80 per bulb - not bad at all!

Create Less Waste:

Reducing waste doesn't have to be difficult! As part of your everyday routine, you can make simple changes that benefit the planet. From carrying a reusable water bottle with you and using cloth bags when shopping to looking for online payment options - there are many ways you can reduce paper consumption in an environmentally friendly way.

Source Your Food Locally:

Eating locally not only supports your local farmers and businesses, but it's also great for the environment! Instead of grabbing those imported items at the supermarket, look around in their local section or visit an outdoor farmer’s market. Not only do you get to enjoy foods grown closer to home with less energy spent on transport - organic is even better as there are no damaging chemicals released.

Use Green Cleaning Products:

Cleaning your home can be a challenge. But when the supermarket cleaners you purchase could have dangerous repercussions for both you and our planet, it's time to investigate greener options! Baking soda and vinegar are surprisingly effective for cleaning - plus safe for you AND Mother Nature too.

Cultivate A Green Yard:

When planning a garden, look for plants that can thrive with minimal water. Plant trees to create cooling shade and protective windbreaks while avoiding harsh herbicides or pesticides. This way you'll cultivate a lush yard that naturally fits right in with the local ecosystem!

Posted in
April 27, 2023

Understanding Home Affordability: Mortgage Rates, Home Prices, and Wages | Latest Information

There has been significant attention paid to the impact of higher mortgage rates on the current challenges faced by homebuyers in terms of affordability. While it is indeed the case that rates have risen significantly from the historic lows observed during the pandemic, it is important to note that home affordability is influenced not only by mortgage rates, but also by home prices and wages. Thus, it is crucial to examine how each of these factors is evolving in order to fully comprehend the state of home affordability presently. Here is the most up-to-date information on this topic.

  1. Although mortgage rates have increased compared to a year ago, they have remained mostly stable within the range of 6% to 7% for almost eight months now. Even a slight variation in mortgage rates can affect your buying potential. Therefore, relying on the expertise of your real estate team is crucial to stay informed about market developments. While predicting future mortgage rate trends is challenging, many professionals anticipate that they will persist at around 6% to 7% in the near term.
  2. The appreciation of home prices has been swift in recent years, driven by the historically low mortgage rates observed during the pandemic that stimulated buyer demand. The imbalance between heightened buyer demand and record-low inventory of homes for sale resulted in an upward push on home prices. However, the current higher mortgage rates have slowed down the pace of price appreciation.
  3. Rising income is currently the most promising aspect of affordability. Higher wages enhance affordability since they lower the percentage of your income needed to pay your mortgage, reducing the amount of your paycheck required for monthly housing expenses. Home affordability hinges on a combination of mortgage rates, home prices, and wages. If you have questions or desire further information, please let us know and we will be happy to discuss the housing market further with you at anytime.  

In summary, if you intend to purchase a home, understanding the critical factors that affect affordability is crucial to make an informed decision. To stay updated on each factor, please just let us know.  

Posted in