Scott Smolen Maryland real estate blog with market updates, community spotlights, and home buying tips

Maryland Real Estate Blog

Scott Smolen's Anne Arundel County and Bowie, Md. Real Estate Blog

Local real estate updates, market insights, community spotlights, and practical home buying and selling advice for Odenton, Gambrills, Crofton, Bowie, Piney Orchard, Two Rivers, and the surrounding Maryland real estate market.

Latest Market Trends

Stay current on mortgage rates, local inventory shifts, pricing trends, and buyer demand across the Maryland real estate market.

Home Selling Advice

Learn how to prepare, price, market, and negotiate when selling a home in today’s local market.

Home Buying Tips

Get practical guidance on affordability, inspections, offers, financing, and buying with confidence.

Community Spotlights

Explore local neighborhoods, market reports, lifestyle features, and community insights throughout the area.

July 18, 2024

Strategies to Reduce Your Mortgage Payment

For many, the mortgage payment stands as the most substantial monthly expense. When finances are tight, this obligation can strain budgets, limiting flexibility for other essential expenditures. Even if comfortably manageable, exploring avenues to alleviate this financial burden can be prudent.

While mortgage payments are typically deemed fixed, avenues exist to lower them, ranging from straightforward adjustments to more intricate maneuvers. Some strategies can be implemented post-mortgage acquisition, while others necessitate pre-planning.

Irrespective of your motivation for seeking a reduced mortgage payment, here are effective strategies to consider:

1. Optimize Pre-Closing Arrangements

Several measures can be adopted to lower your mortgage payment before finalizing the loan. Below are some actions to consider:

- Amplify Down Payment: A larger down payment translates to a diminished loan amount, thereby reducing the subsequent monthly payment. Although it may elongate the home acquisition process, the resultant lower payment can warrant the wait.

- Enhance Credit Score: Elevating your credit score can potentially secure a favorable interest rate, consequently reducing your mortgage payment. Lenders often weigh creditworthiness heavily when setting interest rates, making an improved score instrumental in securing advantageous terms.

- Select Appropriate Mortgage: Choosing the right mortgage type significantly impacts your payment. Contrasting adjustable-rate and fixed-rate mortgages can elucidate payment differentials. While adjustable-rate options might initially offer lower rates, potential future payment escalations underscore the allure of fixed-rate stability.  Additionally, weighing the pros and cons of 30-year versus 15-year mortgages aids in discerning optimal payment dynamics.

2. Pursue Mortgage Refinancing

For existing mortgage holders, refinancing offers avenues to lower payments. It can be achieved through two primary approaches:

- Lengthen Repayment Term: Refinancing to extend your loan term spreads repayment over a longer duration, resulting in reduced monthly payments. For instance, refinancing a 20-year balance into a new 30-year loan alleviates monthly payment burdens.

- Secure Reduced Interest Rate: Refinancing endeavors may yield a lower interest rate, stemming from improved credit or market fluctuations. A diminished interest rate can translate into substantial payment savings. However, securing a lower rate may prove challenging, especially for borrowers who acquired mortgages during historically low-rate periods.

3. Eliminate Private Mortgage Insurance (PMI)

PMI removal can tangibly lower mortgage payments. Strategies to achieve this include:

- Automatic Termination: PMI automatically ceases once scheduled equity thresholds are met – typically 22% based on original property value.

- Request Removal: Upon attaining 20% equity, homeowners can petition for PMI removal, albeit possibly necessitating appraisal expenses.

4. Seek Cost-Effective Homeowners Insurance

Exploring alternative homeowners insurance policies can reduce payment burdens. Leveraging brokers or conducting independent comparisons ensures cost optimization while maintaining adequate coverage.

5. Opt for Mortgage Recasting

Mortgage recasting circumvents refinancing, facilitating payment reduction through lump-sum contributions. This approach recalibrates payment structures based on the modified balance, effectively reducing future payment obligations.

6. Challenge Property Tax Assessments

Disputing inflated property tax assessments offers potential payment relief. Though outcomes are uncertain, successful challenges yield lower tax burdens and subsequently reduced mortgage payments.

7. Utilize Rental Income

Renting out a room can defray mortgage expenses, albeit not technically lowering payments. This income stream offsets mortgage obligations, enhancing affordability. However, tax implications necessitate careful consideration.

8. Consider Temporary Forbearance

For short-term relief, forbearance suspends or reduces mortgage payments, aiding financial respite during hardships. However, long-term affordability concerns persist, with eventual repayment obligations demanding attention.

In Conclusion

Mortgage payments can significantly influence financial well-being, prompting proactive measures to alleviate burdens. Whether through pre-planning or post-acquisition maneuvers, effective strategies abound to mitigate payment pressures, fostering financial stability and flexibility.
 

Posted in Mortgage Tips
July 15, 2024

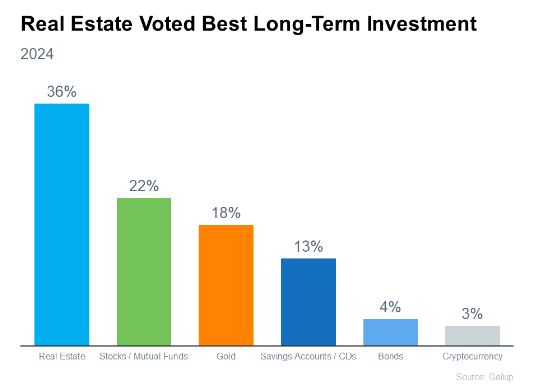
Real Estate: The Reigning Champion of Long-Term Investments

With all the headlines about home prices and mortgage rates, you might wonder if it's still wise to buy a home now or if it's better to keep renting. Here is some information to help ease your mind by showing that investing in a home is still a powerful decision.

According to Gallup experts, real estate has been ranked the top long-term investment for an impressive 12 years in a row, consistently outperforming other investment types like gold, stocks, and bonds.

But why does real estate continue to reign supreme as a top-notch long-term investment? Because, even today, buying a home can be your golden ticket to building wealth over time.

Unlike other investments that can feel like a rollercoaster ride with all the ups and downs and ongoing risk factors, real estate follows a more predictable and positive pattern. History shows that home values usually rise. While prices may vary by market, over time, your house is likely to appreciate in value, significantly boosting your net worth.

As Realtor.com explains: “Homeownership has long been tied to building wealth—and for good reason. Instead of throwing rent money out the window each month, owning a home allows you to build home equity. And over time, equity can turn your mortgage debt into a sizeable asset.”

So, if you are on the fence about whether to rent or buy, remember that real estate is consistently voted the best long-term investment for a reason. If you are ready and able, it may make sense to buy now and start building your wealth.

In Conclusion

When it comes to building lasting wealth, real estate is the way to go. If you are ready to begin your journey toward homeownership, connect with Scott and the Smolen Team today!


July 13, 2024

How to Buy a House in Another State Before Moving

Buying a house in another state can feel like navigating a maze blindfolded. You’re leaving a familiar market and entering one that’s completely new, with different neighborhoods, pricing trends, and legal requirements. Whether you’re relocating for work, investing, or purchasing a vacation home, the process can be daunting, but with the right approach, it’s absolutely doable.

This guide provides a step-by-step approach to buying a house in another state, from researching the local market to closing the deal. Follow these essential tips to help make the process smoother and more manageable.

Can You Buy a House in Another State?

Yes, you can! There are no restrictions on buying real estate in another state for U.S. citizens or permanent residents. Many people purchase homes across state lines for various reasons—whether it’s a new job, an investment, or a vacation property. However, navigating an unfamiliar market adds complexity, so it’s essential to connect with the right professionals to guide you through the process.

Steps to Buy a House in Another State

Here’s a step-by-step breakdown of the process:


1. Define Your Goals and Budget

Start by determining your goals for buying the property. Are you relocating, investing, or planning to buy a vacation home? Once you’ve clarified your purpose, set a budget. Costs like property taxes, closing costs, and insurance can vary significantly between states. It’s a good idea to talk to a mortgage lender to understand your financial limits and secure a pre-approval for financing.

2. Research Your Target Area

Conduct thorough research on the state and area you plan to move to. Explore different neighborhoods to find the best fit based on your lifestyle needs. Websites like Zillow and Realtor.com are great starting points to compare housing prices, local amenities, and crime statistics. You can also join community forums or local Facebook groups to gather insights from current residents.

3. Secure Financing

Before you start house hunting, secure financing by getting a pre-approval from a lender. While you can go with a national bank, working with a local lender in the area you’re moving to can be beneficial—they’ll have a better understanding of the market and can offer more competitive terms.

4. Hire a Local Real Estate Agent

A local real estate agent with experience in helping out-of-state buyers is crucial. They can guide you through the market, provide virtual tours, and negotiate on your behalf. A knowledgeable agent will also help you navigate the nuances of local laws and make sure you’re buying in a neighborhood that aligns with your needs.

5. Start House Hunting

Once you’ve secured financing and hired an agent, the fun part begins—house hunting! Clearly define what you’re looking for, such as the number of bedrooms, proximity to work, or features like a large backyard. Use online listings and virtual tours to narrow down your options before visiting the area in person.

6. Visit the Area

If possible, plan a visit to your target location. While virtual tours are helpful, nothing beats experiencing a neighborhood in person. Walk around, visit local businesses, and talk to potential neighbors. A physical visit can provide crucial insights that might influence your decision.

7. Make an Informed Offer and Negotiate

When you find the right house, your agent will help you make an informed offer based on local market trends and comparable sales. Be prepared to negotiate with the seller on price and other terms, such as closing costs or repair requests.

8. Conduct Due Diligence

Once your offer is accepted, you’ll enter the due diligence phase. This includes getting a home inspection, conducting a title search, and reviewing any homeowners’ association (HOA) rules. If any issues arise, you can renegotiate or ask for repairs.

9. Finalize Financing

After the due diligence phase, finalize your mortgage by locking in an interest rate and submitting any additional paperwork to your lender. Ensure everything is in order to avoid delays in closing.

10. Prepare for Closing

Coordinate with your agent and lender to schedule a closing date. Depending on the state, you may be able to close remotely or use remote online notarization (RON) to sign documents virtually. Once the transaction is complete, the house is officially yours!

11. Consider Temporary Housing

If you’re not ready to move into your new home right away, consider temporary housing options like short-term rentals or extended-stay hotels. This allows you to transition more smoothly and avoid rushing the moving process.

Wrapping Up Your Out-of-State Home Purchase

Buying a house in another state might seem challenging, but with proper planning and a team of local experts, it can be a seamless process. Take the time to research, hire the right professionals, and stay organized throughout the journey. When you're ready to take the next step, contact Scott and the Smolen Team. We’re here to guide you through every stage of your out-of-state home purchase and ensure a smooth transition to your new home.


July 11, 2024

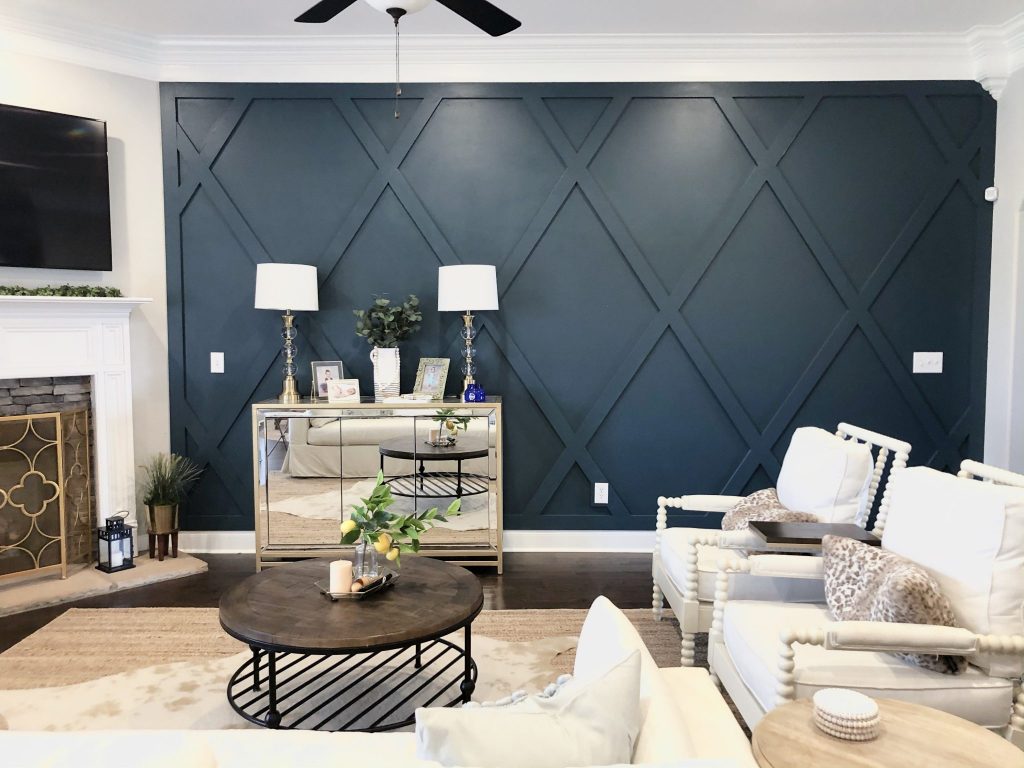
5 Creative Accent Wall Ideas to Elevate Your Home's Interior

In the realm of interior design, the accent wall emerges as a potent tool for infusing personality and charm into any living space. Elevating a room from mundane to captivating, a well-executed accent wall can breathe life into your surroundings, adding depth, texture, and intrigue. Whether you're embarking on a home makeover or simply looking to refresh your condo's interior, this article delves into five distinct accent wall ideas guaranteed to redefine your space.

1. Strategic Placement for Maximum Impact

Selecting the optimal location for an accent wall is a strategic move that can profoundly influence the ambiance of a room. Experts like Kris and Paul Masson from Boots Up Nashville advise placing your accent wall strategically, suggesting the first wall upon entering a space or the wall behind a key piece of furniture as ideal options.

2. Embrace the Trend of Hardscaping

Hardscaping an accent wall introduces an edgy and industrial aesthetic, harnessing the raw allure of materials like brick, stone, or concrete. George Markoustas of ABLAZE Design Group champions accent walls as perfect canvases for showcasing personal style, advocating for hardscaping to accentuate architectural elements or add tactile texture. Victoria King of Victoria King Design highlights the ease of refreshing walls with thin bricks for a quick update.

3. Transform with Wallpaper

Wallpapers offer a versatile medium for accent walls, boasting an array of patterns, textures, and colors. Tim Schanz of Persnickety Paperhanger praises wallpaper as a means to introduce color, pattern, or texture without overwhelming the entire space. Oleksandr Bezhenar of Captain Wallpaper underscores the limitless options available, from exclusive patterns to natural materials, advising professional installation to avoid mishaps.

4. Infuse Warmth with Wood Wooden accent walls exude warmth and timeless elegance, catering to a spectrum of interior styles. Ryan Smith of Mid Mod Phoenix extols wooden accents for their timeless sophistication, advocating for simple, sleek wood planes or customizable built-in shelving to complement existing decor seamlessly.

5. Harness the Power of Paint

Paint remains the simplest yet most impactful means of creating an accent wall. A carefully selected color can set the mood of a room, imbuing it with depth and character. Chris Fein of Forward Design | Architecture emphasizes the importance of painting the entire wall for maximum effect, while Andy of Windy City Painters suggests experimenting with dark paints or custom textures like limewash or Venetian plaster, stressing the significance of skilled painters for flawless execution.

By embracing these creative accent wall ideas, you can transform your living space into a haven of style and sophistication. Whether you opt for the rugged allure of hardscaping, the vibrant versatility of wallpaper, or the timeless elegance of wood, each approach offers a unique opportunity to infuse your home with personality and charm. So, unleash your creativity and embark on a journey to redefine your space, one accent wall at a time.


July 8, 2024

Exploring Tax Implications of Cash-Out Refinancing

Cash-out refinancing presents an opportunity to leverage your home's equity for various purposes, ranging from home renovations to educational expenses or medical bills. However, it's essential to be aware of potential tax implications that may arise in certain scenarios.

Are Cash-Out Refinances Taxable?

No, the funds obtained through a cash-out refinance are not subject to taxation. Essentially, the money received from this type of refinance constitutes a loan against your home's equity, and loan proceeds, including those from HELOCs and home equity loans, are not categorized as income.  Furthermore, you might even qualify to deduct a portion of the interest paid on your cash-out refinance.

Tax Regulations for Cash-Out Refinances

For those intending to itemize deductions, the interest paid on the new mortgage can be deducted from taxable income. However, this deduction is subject to specific conditions, including using the cashed-out funds for "capital improvements" on your home.

Capital improvements encompass permanent enhancements or renovations that increase your property's value, prolong its lifespan, or adapt it for new purposes. It's advisable to consult with a tax professional to ensure that your intended projects qualify for deduction. Saving receipts and pertinent documentation associated with your projects is crucial for substantiating your claims during tax filing.

According to Ralph DiBugnara, senior vice president of Cardinal Financial in Charlotte, utilizing funds to enhance your home's value while benefiting from tax deductions constitutes a double advantage.

Strategies for Maximizing Tax-Deductible Interest from Cash-Out Refinances

The manner in which you allocate the proceeds from a cash-out refinance can significantly impact the tax-deductible interest. Interest on the new mortgage is more likely to be fully deductible if the funds are directed towards home improvements that enhance your property's value. Here are some strategies to maintain a tax deduction:

1. Invest in Capital Home Improvements: Deductible projects include additions like swimming pools, bedrooms, or bathrooms, as well as enhancements to roofing, windows, or security systems.

2. Establish a Home Office: Adding a home office can qualify for a deduction, especially if you're self-employed or operate a business. However, specific criteria, such as regular and exclusive usage for business purposes, must be met.

3. Enhance Rental Properties: Expenses for improvements and repairs on rental properties remain tax-deductible, allowing you to use cash-out proceeds to increase resale value or rental income.

Additionally, mortgage points paid during a cash-out refinance, also known as discount points, can be deductible over the loan's duration, albeit not in a lump sum.

Understanding Mortgage Interest Deduction Limits

The ability to deduct interest on the entire new mortgage is contingent upon using the cash-out funds for capital improvements. If the funds are allocated elsewhere, such as debt repayment or vehicle purchases, interest deduction may be limited to the original mortgage balance.

Changes in tax regulations, particularly since 2018, have imposed caps on mortgage interest deductions. These caps dictate the maximum deductible amount based on your filing status and mortgage debt.

Risks and Alternatives

While cash-out refinancing offers a cost-effective means of accessing cash, it also entails assuming a larger loan obligation. Failure to comply with stringent deduction rules or overextension could lead to unforeseen tax consequences or financial difficulties.

To mitigate risks, it's advisable to consult with a tax advisor before committing to a cash-out refinance. Furthermore, consider alternative options such as home equity loans or HELOCs, which maintain your primary mortgage while providing access to equity.

In conclusion, understanding the tax implications of cash-out refinancing is crucial for making informed financial decisions and maximizing potential benefits while minimizing risks.


July 5, 2024

Benefits of Condo Living: A Guide for First-Time Homebuyers

Struggling to find a first home that aligns with your budget? Consider condominiums, or condos. While condos are typically smaller than single-family homes, they offer cost advantages.

Recent data from the National Association of Realtors (NAR) indicates that condos are generally more affordable. If you're open to a smaller living space and eager to enter homeownership this year, exploring condos could be financially advantageous.

Beyond the budget-friendly aspect, condos offer a range of perks. According to Rocket Mortgage, they provide community living and are often situated in walkable urban areas, making them attractive to first-time buyers seeking convenience without extensive upkeep.

Let's delve into why condos are appealing for newcomers to the housing market, as outlined by Bankrate:

1. Low maintenance: Condos require minimal upkeep, sparing homeowners from tasks like lawn care or roof repairs. Your real estate agent can detail any associated fees and maintenance responsibilities.

2. Equity building: Purchasing a condo allows you to accumulate equity over time, enhancing your net worth as property values appreciate.

3. Added amenities: Many condos offer amenities such as pools, dog parks, or parking facilities, all maintained by the condominium association.

4. Community atmosphere: Condo living fosters a sense of community, with neighbors in close proximity and opportunities for social gatherings and events.

Remember, your first home needn't be permanent. The crucial step is initiating homeownership to start accruing equity, which can facilitate future property transitions. Ultimately, condo living represents a lifestyle choice with added benefits in today's housing market. If condo living resonates with you, it's worth exploring further.

In conclusion, considering condos in your home search could be advantageous. Reach out to Scott and the Smolen Team to explore available options in your desired area!


July 2, 2024

Housing Market Outlook: Predictions for the Second Half of 2024

As we enter the latter half of 2024, here’s what experts anticipate for home prices, mortgage rates, and home sales.

Moderate Growth Expected in Home Prices

Home prices are projected to continue increasing at a more moderate pace. Jessica Lautz, Deputy Chief Economist at the National Association of Realtors (NAR), highlights the key factor driving this trend: “One thing that appears certain is that home prices will continue to rise, driven by persistent low housing inventory.” While there has been an increase in inventory compared to recent years, overall supply remains limited. This scarcity will likely exert upward pressure on prices. If you’re considering a purchase, the upside is that price spikes seen during the pandemic are unlikely. However, prices are expected to continue their ascent, albeit at a slower rate. Acting sooner rather than later could potentially yield long-term savings, as experts suggest home values will appreciate post-purchase.

Forecasted Decrease in Mortgage Rates

Encouraging news for both buyers and sellers is the anticipated slight decline in mortgage rates, according to forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and NAR. Even a modest reduction in rates can significantly impact monthly payments for buyers. For sellers, lower rates may attract more buyers to the market, potentially facilitating quicker sales and higher offers. This shift could also prompt hesitant sellers to list their homes.

Steady Projected Home Sales

Home sales in 2024 are projected to remain stable, with potential for a slight increase over last year’s figures. The combined forecast from experts averages around 5 million sales for the year, a marginal uptick from 2023.

Lawrence Yun, Chief Economist at NAR, points to several factors driving this trend: “Job growth, stable mortgage rates, and increased inventory from pent-up sellers are expected to stimulate sales.” With more homes available and anticipated lower mortgage rates, the market is poised to facilitate more transactions compared to the previous year, allowing more individuals to achieve their moving goals.

Bottom Line

If you’re navigating the current market and have questions or need assistance, reach out to Scott and the Smolen Team. They can provide expert guidance tailored to your specific needs and help you make informed decisions in today’s evolving housing landscape.


June 24, 2024

Have Property in Probate? Important Tips to Ensure Your Property Qualifies for Financing

Selling a property in probate is a complex process that requires careful planning and preparation. One of the most critical factors in securing a successful sale is ensuring that the property qualifies for financing. By making the property eligible for various financing options, you can significantly expand your pool of potential buyers, increasing the chances of a favorable sale.

Why Financing Eligibility Matters

When selling a home that’s part of a deceased estate, it's important to remember that many buyers rely on mortgages or other loan packages to purchase properties. If the property you’re selling doesn’t meet financing criteria, you could miss out on a large segment of potential buyers. Ensuring the property is market-ready and financing-eligible not only makes it more attractive to buyers but also increases the likelihood of receiving competitive offers.

Preparing for Conventional Loans

Conventional loans are a popular financing option for many buyers because they are backed by industry giants like Fannie Mae and Freddie Mac. However, to qualify for a conventional loan, both the buyer and the property must meet strict criteria. Buyers typically need good credit scores, steady income, and manageable debt levels. For the property, this means it must be in good condition, free of major repairs, and competitively priced in the market. Ensuring the property meets these standards can make it easier for buyers to obtain financing, which in turn makes your property more appealing.

Exploring FHA and VA Loans

In addition to conventional loans, there are other financing options that can attract a wider range of buyers. Federal Housing Administration (FHA) loans and Veterans Affairs (VA) loans are two such options. FHA loans are particularly attractive because they have more lenient qualification requirements compared to conventional loans, making them accessible to a broader range of buyers. VA loans, on the other hand, offer exceptional benefits to veterans, making them a preferred choice for those who have served in the military. However, properties must meet specific criteria to qualify for these loans, such as minimum square footage and appropriate pricing. Ensuring your property meets these requirements can make it eligible for these attractive financing options, thus broadening its market appeal.

The Importance of Working with an Experienced Real Estate Agent

Navigating the sale of a probate property can be overwhelming, especially when trying to ensure it qualifies for various financing options. This is where the expertise of a knowledgeable real estate agent becomes invaluable. An agent with experience in probate sales can guide you through the process, helping you prepare the property to meet financing criteria. They can also provide insights into the most effective strategies to market the property, attract qualified buyers, and secure the best possible price. By working with a professional, you can increase the likelihood of a successful and timely sale.

Final Thoughts

Selling a property in probate requires a thoughtful approach, especially when it comes to ensuring the property qualifies for financing. By making the necessary preparations and working with an experienced real estate agent, you can expand your buyer pool, attract competitive offers, and achieve a successful sale. Remember, the key to a smooth probate sale is making the property as appealing and accessible as possible to a wide range of buyers. For expert guidance on preparing your probate property for sale and ensuring it qualifies for financing, reach out to Scott and the Smolen Team. We're here to help you navigate the complexities of probate sales and secure the best outcome for your property.


June 22, 2024

Selling Your Parents’ Home After They Pass Away: Reviewing the Insurance and Securing the Property

If your parents' home will remain vacant until it is sold, it's crucial to review the current home insurance policy and ensure the property is secured. A vacant home faces increased risks, such as break-ins and vandalism, and most standard insurance policies will not cover this damage unless you have a vacant home insurance policy in place.

Review the Home Insurance Policy

If your parents had a homeowners insurance policy, contact the insurance provider immediately. You will need to inform them of your parents' passing and inquire about switching to a vacant home insurance policy. These policies offer protection tailored to the unique risks of an unoccupied house, ensuring you are covered while the property remains on the market.

Secure the Property

While you are waiting for the home to sell, taking additional steps to safeguard it from potential threats is a good idea. Here are several actions to consider:

  • Set Aside Important Documents: Locate and secure any essential financial and legal paperwork, such as asset statements, wills, or life insurance policies. These documents will likely be needed to settle your parents' estate and keeping them safe is vital.
  • Lock Away Valuables: Work with the other heirs to identify any valuables within the home. Secure these items in a safe location, and document everything to avoid potential disputes. This transparency helps ensure that all parties are informed of what is being safeguarded.
  • Regularly Pick Up Mail: An overflowing mailbox signals to thieves that the home is vacant. Regularly collect the mail, or, if that is not feasible, use the post office’s mail hold service or have it forwarded to your address.
  • Change the Locks: Over the years, neighbors, service providers, or family friends may have obtained keys to the house. Even though most likely pose no threat, it is wise to change the locks to limit access while the home is unoccupied. This way, if anything goes missing or gets damaged, you will have better control over who had access to the property.
  • Ensure Doors and Windows Are Locked: Unlocked doors or windows can easily invite trespassers. Double-check all entry points, and for extra security, place dowel rods in window and sliding door tracks to prevent them from being opened from the outside.
  • Install a Security Camera: If you are unable to visit the house frequently, setting up a security camera or video doorbell that allows you to monitor the property remotely. With motion detection and recording capabilities, you will be notified of any unexpected activity. Keep in mind that you will need to maintain internet service to access live feeds and alerts.

In Conclusion

Securing your parents’ home and ensuring proper insurance coverage are essential steps in safeguarding the property until it sells. Taking these precautions helps protect the home from potential risks and provides peace of mind during the estate settlement process. When you are ready to begin the selling process, reach out to Scott and the Smolen Team for expert guidance. They can help navigate the complexities of selling an inherited home, ensuring a smooth and successful transaction.


June 20, 2024

Understanding Mortgage Rate Locks

Securing a mortgage rate lock is like safeguarding your financial future when embarking on the journey of homeownership. By locking in your interest rate, you ensure that it remains unchanged from the time of agreement to the closing date, provided there are no alterations to your application. Let’s delve deeper into the world of mortgage rate locks to understand when and how to utilize them effectively.

Understanding the Mechanism of Mortgage Rate Locks

Picture this: you've found your dream home, and you're ready to take the plunge into homeownership. Amidst the whirlwind of paperwork and decisions, a mortgage rate lock emerges as a beacon of stability. Essentially, a rate lock enables you to freeze your mortgage interest rate while navigating the labyrinth of refinancing or purchasing a home. This means that regardless of the market fluctuations, your interest rate remains constant until the closing day, provided you adhere to the specified timeframe and uphold the integrity of your application.

However, it's crucial to ensure that your rate lock duration aligns with your anticipated timeline for closing on the loan. Extensions can be costly, so it's wise to plan ahead. Additionally, any modifications to your application, such as changes in loan amount or credit score, may impact your locked rate. Unless your lender offers a float-down rate lock option, you could miss out on potential savings if interest rates drop post-lock agreement.

Introducing the Float-Down Rate Lock

Enter the float-down rate lock, a savvy alternative for those wary of missing out on favorable rate adjustments. This option allows borrowers to secure their rate while retaining the flexibility to lower it under specific conditions. Should market rates take a nosedive during the lock period, borrowers can capitalize on the opportunity to snag a lower interest rate, albeit at an additional cost determined by the lender.

Duration and Flexibility of Rate Locks

Rate locks typically span 30, 45, or 60 days, with the possibility of extensions depending on prevailing market conditions. However, extensions may entail supplementary fees, even if the initial lock period was complimentary. The timing of your rate lock is pivotal, influencing the total cost of your mortgage. Factors such as occupancy plans, down payment or equity amount, and loan term length further shape the rate dynamics.

Determining the Optimal Time to Lock Your Rate

Deciding when to lock in your mortgage rate hinges on various factors, including your risk tolerance and market projections. For prospective homebuyers, the timing of rate lock initiation may be subject to specific conditions tied to the home buying process, such as contingencies, house readiness, or the closing date. Conversely, individuals contemplating refinancing must assess whether a rate lock aligns with their financial objectives, be it breaching the break-even point or securing a lower mortgage rate.

Navigating the Rate Lock Process

If you're ready to take the plunge into rate locking territory, the process is straightforward. Start by ensuring your credit score is in tip-top shape and setting aside funds for the down payment. Next, submit your mortgage loan application, review the Loan Estimate provided by your lender, and weigh your rate lock options. You can either secure your rate and proceed with the chosen lender or explore alternative rates elsewhere.