Scott Smolen Maryland real estate blog with market updates, community spotlights, and home buying tips

Maryland Real Estate Blog

Scott Smolen's Anne Arundel County and Bowie, Md. Real Estate Blog

Local real estate updates, market insights, community spotlights, and practical home buying and selling advice for Odenton, Gambrills, Crofton, Bowie, Piney Orchard, Two Rivers, and the surrounding Maryland real estate market.

Latest Market Trends

Stay current on mortgage rates, local inventory shifts, pricing trends, and buyer demand across the Maryland real estate market.

Home Selling Advice

Learn how to prepare, price, market, and negotiate when selling a home in today’s local market.

Home Buying Tips

Get practical guidance on affordability, inspections, offers, financing, and buying with confidence.

Community Spotlights

Explore local neighborhoods, market reports, lifestyle features, and community insights throughout the area.

Oct. 7, 2024

Why Now Is the Time to Buy a Home

After months on the sidelines, many homebuyers who faced high mortgage rates and affordability challenges now have a golden opportunity to make their move. With rates trending downward, today’s market presents a unique sweet spot for buyers—one that may not last long.

If you have been considering a move, here are compelling reasons to reconsider waiting.

Assessing the Market

As you contemplate whether to buy now or wait, think about this: What do you anticipate others will do?

If mortgage rates continue to decline, as experts predict, more buyers are likely to re-enter the market. A recent survey from Bankrate indicates that over half of homeowners would be inclined to buy this year if rates fall below 6%. With current rates already in the low 6% range, we’re close to that threshold. The reality is, once rates dip into the 5% range, the number of active buyers will likely increase, leading to more competition.

Increased demand could drive home prices up, potentially offsetting any benefits from a lower interest rate. As Nadia Evangelou, Senior Economist at the National Association of Realtors (NAR), notes:

“The downside of increased demand is that it puts upward pressure on home prices as multiple buyers compete for a limited number of homes. In markets with ongoing housing shortages, this price increase can offset some of the affordability gains from lower mortgage rates.”

What This Means for You

Right now, you have the chance to get ahead of the curve. Today’s market is advantageous for buyers because many are still waiting, resulting in less competition for you. Affordability has already improved significantly. Recent declines in mortgage rates have made homeownership more accessible. According to Mike Simonsen, Founder of Altos Research: “Mortgage payments on the typical-price home are 7% lower than last year and are 13% lower than the peak in May 2024.”

While the supply of homes for sale remains low, it’s higher than it’s been in years. Ralph McLaughlin, Senior Economist at Realtor.com, reports: “The number of homes actively for sale continues to be elevated compared with last year, growing by 35.8%, a 10th straight month of growth, and now sits at the highest since May 2020.”

This means you have more options than ever before. With fewer buyers in the market, improved affordability, and a greater selection of homes, you can find the right one before competition heats up.

The Risks of Waiting

If you are holding out for the “perfect” time to buy, be aware that timing the market is incredibly challenging. The longer you wait, the greater the risk that conditions will change—and not in your favor. Greg McBride, Chief Financial Analyst at Bankrate, advises: “It’s one of those things where you should be careful what you wish for. A further drop in mortgage rates could bring a surge of demand that makes it tougher to actually buy a house.”

Bottom Line

Now is the time to act—don’t wait for increased competition and higher prices. You have a unique opportunity to buy a home in this advantageous market. Reach out to Scott and the Smolen Team today to discuss your options and take the next step!
 

Oct. 4, 2024

Divorce and Real Estate: A Comprehensive Guide to Property Division

Divorce is a life-altering event that touches every corner of life—emotionally, financially, and practically. One of the most challenging aspects is dividing shared assets, particularly real estate, which can be more complicated than other possessions. The process requires a clear understanding of both legal frameworks and the real estate market.

If you are facing this difficult transition, we’re here to support you with expert guidance. As your trusted real estate advisor, we will help ease the burden of property division and ensure a smooth real estate transition during and after your divorce. With years of experience in helping divorcing couples, we are prepared to manage the complexities that arise, allowing you to focus on your future.

The Emotional and Practical Realities of Divorce

Divorce is not just about dividing assets; it’s also about letting go of a shared life, and real estate often holds deep emotional value. For many couples, real estate is not just a financial investment; it’s the family home where memories were made, the vacation property that represented future dreams, or even a rental property symbolizing joint accomplishments. These personal connections make the division of real estate during divorce more than just a legal issue. It becomes an emotional process that requires careful handling. We understand the weight of this situation, and our goal is to help you make decisions that honor both your emotional and financial well-being.

Property Division Laws: What You Need to Know

In the U.S., property division laws vary by state and generally fall into two categories: community property and equitable distribution.

- Community Property States: These states mandate a 50/50 division of assets acquired during the marriage, including real estate.

- Equitable Distribution States: In these states, assets are divided based on fairness, which doesn’t always mean an equal split. The court considers factors like the length of the marriage, each spouse's financial contribution, and future earning potential to arrive at a division that feels just to both parties.

Understanding which system applies to you is critical when navigating property division, as it directly impacts how your real estate holdings will be split.

What Counts as Divisible Property?

Real estate is often one of the most valuable assets a couple owns. When considering property division, it’s important to distinguish between separate property (assets owned before the marriage or received as gifts or inheritances) and marital property (assets acquired during the marriage).

- Marital Property: This typically includes the family home, vacation homes, and rental properties purchased during the marriage. In some cases, even the income generated from real estate investments can be included in the marital estate.

- Separate Property: If a spouse owned a property before the marriage, it might be considered separate, though appreciation in value during the marriage could make a portion of it subject to division.

Approaches to Property Division

Divorcing couples have several options when it comes to dividing real estate:

1. Sell the Property and Split the Proceeds: One of the simplest methods is to sell shared real estate and divide the profits. This approach can provide both parties with a clean financial break.

2. Buyout: In some cases, one spouse may choose to buy out the other’s share of the property, allowing one person to keep the home while compensating the other financially.

3. Co-Ownership Post-Divorce: Some couples choose to continue owning property together post-divorce, especially in cases where children are involved. This arrangement requires strong communication and a formal agreement to avoid future disputes.

Factors That Influence Property Division

Courts consider several factors when determining how to divide real estate in a divorce, including:

- Contributions to Property: This can include financial contributions (such as mortgage payments) or contributions through home maintenance and upkeep.

- Duration of the Marriage: In longer marriages, courts are more likely to split assets equally.

- Financial Situation of Each Spouse: The court will look at the financial standing of both parties, including income and earning potential, to ensure a fair distribution.

- Child Custody Arrangements: If children are involved, the custodial parent may be granted the family home to provide stability.

Special Considerations: Valuation, Taxes, and Joint Ownership

It is essential to get a proper valuation of your real estate before entering property division negotiations. Working with an appraiser ensures that both parties have a clear understanding of the property’s market value. Additionally, there are tax implications to consider, such as capital gains tax if you sell the property. Proper planning can help minimize financial surprises.

Working with Professionals

Dividing real estate during a divorce is complex and often emotional, which is why having the right team of professionals is crucial. A real estate agent with experience in divorce situations can provide valuable market insights and facilitate a fair and smooth transaction. You will also need a divorce attorney to handle the legal aspects, and potentially a financial advisor to guide your post-divorce financial planning.

Ready to Move Forward?

At the Scott Smolen Team, we specialize in guiding clients through these challenging times. Whether you are looking to sell your marital home, divide rental properties, or start fresh with a new property, we can help you navigate every step of the process.


Oct. 2, 2024

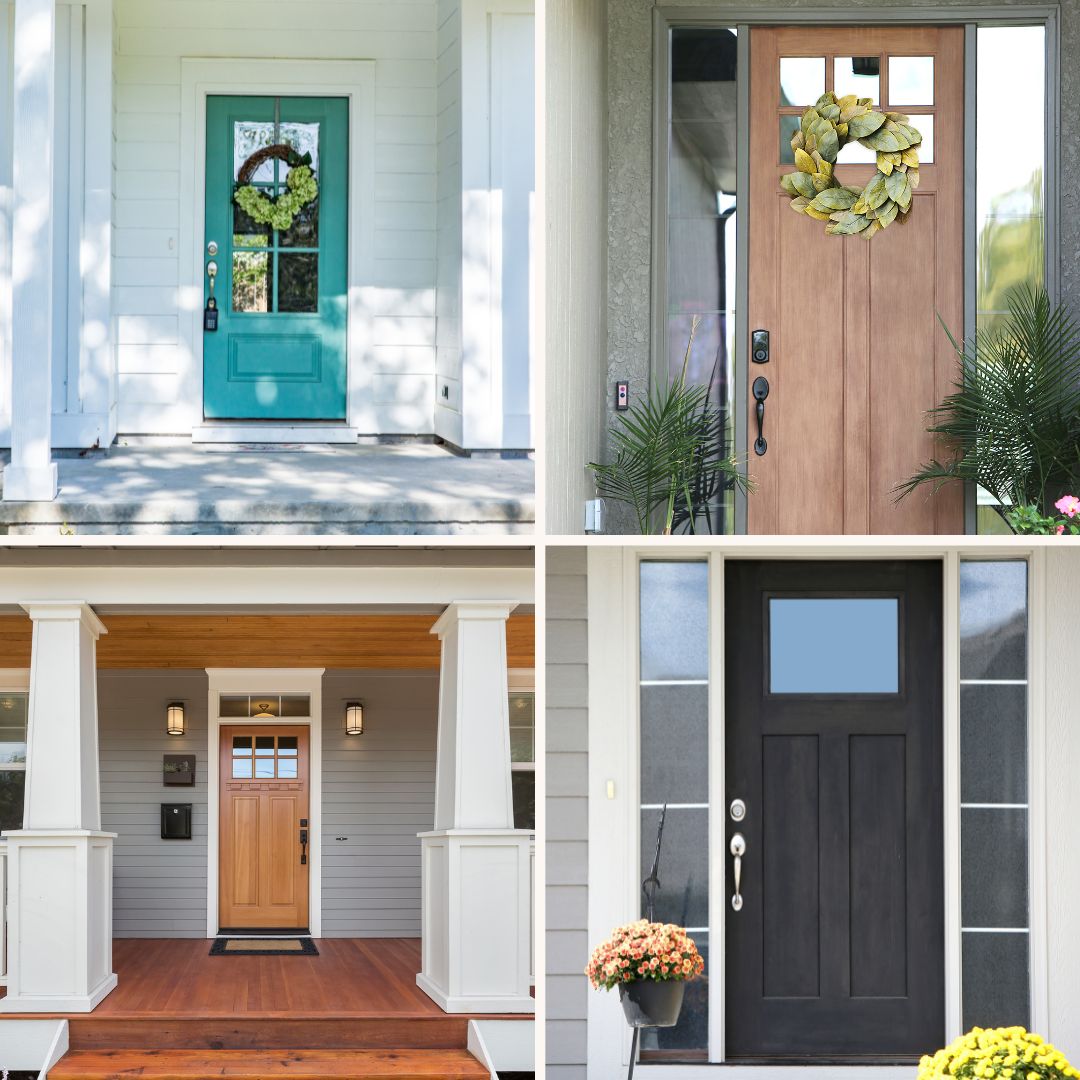
Choosing the Perfect Front Door

Your home's front door is more than just an entry point; it is the gateway to your personal space. It plays a pivotal role in making a lasting first impression, ensuring security, and enhancing energy efficiency. In this article, we delve into the six essential considerations you should keep in mind when choosing a front door that complements your home's style while providing safety and top-notch performance.

Whether you are closing on a new home, planning updates, or embarking on a fixer-upper project, this guide will provide you with the insights needed to select the perfect front door for your home.

1. Prioritize Material and Durability

Choose materials like wood, fiberglass, steel, or aluminum for your front door. Each material has its set of advantages and disadvantages related to durability, maintenance, and appearance. While wood offers a classic and timeless appeal, it may require more frequent maintenance. On the other hand, steel and fiberglass are more resistant to wear and tear, with aluminum doors offering lightweight durability.

2. Enhance Your Home's Curb Appeal

The front door is one of the first things visitors notice about your home, making it a central component of curb appeal. The design, color, and style of your door should match and enhance your home's exterior. Select a door that reflects your personal taste and complements the architectural integrity of your house to elevate its overall appearance. Billy Cline, president and CEO of Your New Door, emphasizes how a well-selected front door can add to a property's value while acting as a portal from the outside world, setting the tone for what's to come.

3. Prioritize Security Features

Security should be a top consideration when choosing a front door. Ensure it comes with keyless entry, deadbolts, and other security mechanisms to provide peace of mind. Rose Reif, brand and business manager for Window Works Co., suggests adding obscured glass to enhance privacy while allowing natural light.

4. Consider Sun Exposure

Since investing in a front door can come at a higher price, ensure that the material you select is resistant to sun exposure. Doors that receive direct sunlight may require materials like iron, fiberglass, or clad doors, as recommended by Billy Cline.

5. Match Your Door Style to Your Home

Select a door style that complements your home's architectural design. Whether your home has a modern, traditional, or colonial facade, there is a door design to match. Ensure the style, lines, and details harmonize with your home's character to create an aesthetically pleasing exterior. Inna Shellkopf with Brownstone Doors Co. advises that when replacing a front door on a historic property, research the appropriate door style from the era in which the property was built. Pay attention to detail, such as door hardware, which can further enhance the overall appearance. Benjamin Eli with RUS Doors Inc. suggests that front doors can set the tone for the house's design style, making it a great starting point for your renovation.

6. Focus on Energy Efficiency

Opt for doors with good insulation, weather stripping, and energy-efficient glass options to save on heating and cooling costs. A well-insulated door significantly reduces energy loss, creating a more comfortable living environment and lower utility bills. Moreover, investing in an energy-efficient door helps reduce your carbon footprint, contributing to eco-friendly living.

Final Thoughts on Choosing a Front Door

Crafting a cohesive design for your home involves careful consideration of every detail, including your front door. As Greg Kaminski of Craftwood Doors and Windows highlights, the front door makes a lasting first impression and communicates the residents' design preferences. From enhancing curb appeal and security features to selecting the right material and style, these six tips should guide your next project.


Sept. 30, 2024

National Market Update: Rising Home Sales, Lower Prices, and Positive Trends for Buyers

The national real estate market is showing signs of positive momentum, with new home sales up nearly 10% compared to last year and median home prices dropping by almost 5%. This shift is creating a more favorable environment for buyers. While August saw a slight dip in sales, July posted the largest monthly increase in nearly two years. As more buyers enter the market, with mortgage applications on the rise, it's clear that affordability is improving—a trend that could shape the housing landscape in the months to come.

National Update: New Home Sales Surge, Prices Ease

The national real estate market is experiencing a dynamic shift as new home sales have risen nearly 10% compared to last year. In contrast, the median home price has decreased by almost 5%, providing potential buyers with a more favorable pricing environment. While sales saw a slight dip in August following a significant surge in July, the July numbers marked the largest monthly increase in nearly two years—an encouraging trend for the market.

The Pending Home Sales Index, which tracks signed contracts for existing homes, also saw a slight uptick in August. The National Association of Realtors pointed out that this increase signals a modest improvement in housing affordability, a positive sign for buyers.

More buyers are entering the market, as evidenced by the fact that mortgage applications for home purchases have risen for three consecutive weeks. With refinances surging as well, overall mortgage applications are at their highest level in more than two years. This increase is giving many the opportunity to lock in favorable rates, even as the market continues to shift.

Review of Last Week: Market Moderation and Global Stimulus

Last week, a combination of moderating inflation and China's surprise economic stimulus measures gave the stock market a boost. Traders are now more confident that the Federal Reserve will implement additional rate cuts, and they are optimistic about global economic growth prospects.

China introduced a series of economic stimuli on Tuesday to bolster their slowing economy. Meanwhile, the U.S. inflation rate, measured by the PCE Price Index, showed a slowdown in consumer price increases during August. This has led to speculation that the Fed will reduce rates in the coming months to maintain economic momentum.

Despite a sharp decline in September consumer confidence—the largest in more than three years—business spending rebounded in August, and consumer spending recorded a small gain. The result was another positive week for the stock market: the Dow Jones finished up 0.6% at 42,313, the S&P 500 up 0.6% to 5,738, and the Nasdaq saw the largest gain of 1.0%, ending at 18,120.

While the bond market remained relatively flat, longer-term bonds showed some weakness. The 30-year UMBS 5.0% saw a slight drop to $99.32. On the mortgage front, the national average 30-year fixed mortgage rate inched down to its lowest point in two years, but experts warn that rates can be volatile, so it's wise to stay in close contact with your mortgage professional.

Market Insights: Positive Signs for Buyers

In a promising development for buyers, new real estate listings surged 8% compared to the same time last year, sending total active inventory 33% higher. Additionally, the median listing price dropped by 1%, making the market slightly more accessible for those looking to purchase a home.

This Week's Economic Forecast

Looking ahead, economists predict that overall construction spending will show a modest gain for August, though the focus will likely be on residential numbers. The manufacturing sector is expected to remain in contraction territory, while the service sector is predicted to stay just above the growth threshold. The much-anticipated September jobs report is forecast to show fewer new nonfarm payrolls, with the unemployment rate holding steady at 4.2%.

Federal Reserve Watch

Following the recent PCE inflation report, there is growing speculation that the Federal Reserve will cut interest rates by half a percentage point in November, with additional quarter-percent cuts expected in December and January. This potential easing of monetary policy could further stimulate both the housing and broader economic markets.

Contact Us for Expert Real Estate Guidance!

As the real estate market continues to evolve, it’s important to have the right guidance to make informed decisions. Whether you're looking to buy, sell, or just have questions about the current market, Scott and the Smolen Team are here to help. Feel free to reach out to us with any of your real estate or market questions and let us assist you in navigating today’s market with confidence!


Sept. 27, 2024

Does Upgraded Lighting Add Value to a Home for Sale?

Lighting is not just about illumination—it sets the mood and enhances the appearance of your home. As winter approaches, with its shorter days and gloomy weather, many sellers are considering how to brighten their homes through improved lighting. Here is why investing in upgraded lighting could benefit you when selling your property.

Is Upgrading Lighting Worth It?

Enhanced lighting can significantly impact a buyer’s perception of your home. Jeannie Do, an Interior Design expert with RE/MAX Professionals, notes that lighting is a crucial aspect of home design. “A well-lit room feels more spacious and welcoming,” she explains. “Bright lighting can make a room seem larger and cleaner, while softer lighting creates a cozy, intimate atmosphere.”

Do advises that a home tour starts positively when buyers notice a bright and inviting space. “When a home is well-lit, it feels like a fresh canvas, helping buyers envision their future there,” she says. However, dim lighting in areas like a primary bathroom can enhance a spa-like ambiance.

Update Lighting for a Modern Feel

Outdated lighting can make even well-designed spaces seem less appealing. “Not updating your lighting is like wearing a stylish suit with flip flops,” Do compares. “The look is almost there, but something’s off.”

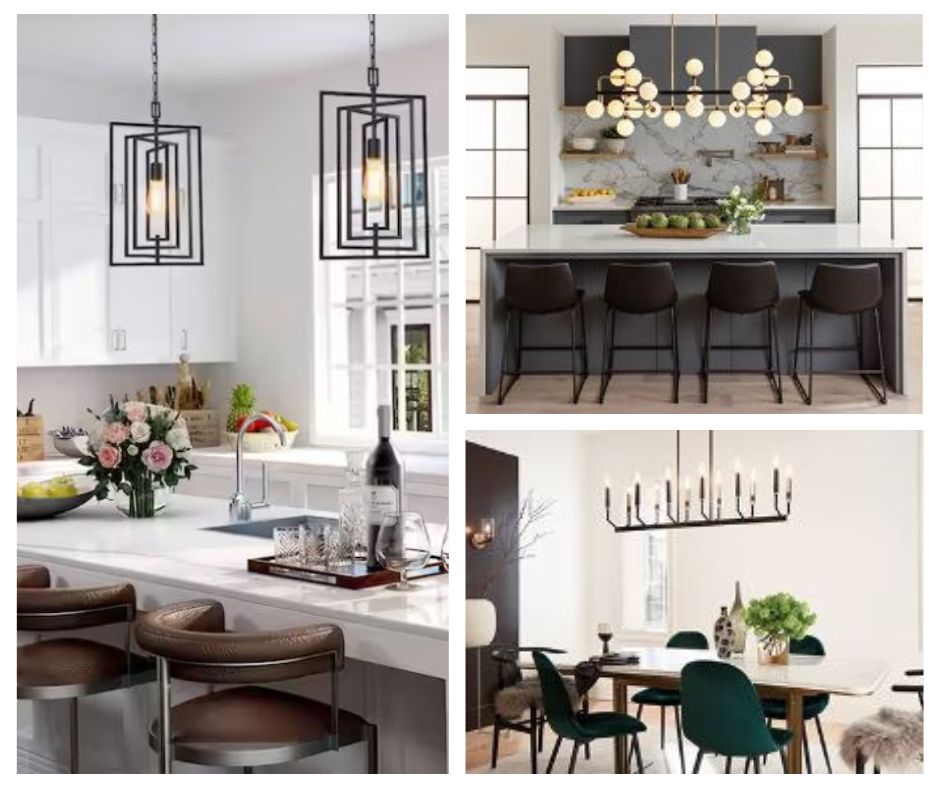
Consider modernizing light fixtures, such as updating pendant lights over a kitchen island, adding recessed lighting, or replacing outdated lamps. Match the style of your fixtures to your home’s décor to maintain visual harmony.

Strategic Lighting Design

Effective lighting involves more than just brightness. It includes:

  • Ambient Lighting: Provides overall illumination and sets the room’s mood.
  • Task Lighting: Offers focused light for specific activities, like cooking or reading.
  • Accent Lighting: Highlights special features, such as artwork or architectural details.

Do suggests integrating these types to create a well-rounded lighting design. For example, outdoor sconces can enhance curb appeal, while strategic lighting in home offices can support productivity, especially for remote workers.

Consider Modern Buyer Needs

The shift to remote work has increased demand for home offices with ample natural light. Ensure your workspace or multi-purpose room is well-lit to appeal to today’s buyers. Brighten these areas with updated fixtures or strategic lamps to illustrate their functionality.

Final Considerations

If you plan to take certain light fixtures with you, inform your real estate agent to avoid surprises. The right lighting can highlight your home’s best features and make it more attractive to buyers. Ready to make your home shine? Contact Scott and the Smolen Team to get expert advice on staging, selling, and everything in between.


Sept. 24, 2024

Three Key Steps to Master Homeownership While Self-Employed

Purchasing a home while self-employed may seem like a challenging feat. After all, the ebb and flow of income can make mortgage lenders hesitant compared to a consistent paycheck. However, it's far from impossible. Freelancers and small business owners can absolutely secure the home of their dreams with a little extra preparation. If you're considering navigating the real estate market while being your own boss, pay close attention. Here are three crucial steps that every self-employed aspiring homebuyer should follow to position themselves as a prime candidate for approval. By heeding these guidelines, you'll be well on your way to securing that coveted pre-approval.

1. Accumulate at Least Two Years of High-Net Tax Returns

Banks, in the absence of a W-2 form, rely on your tax returns to substantiate your take-home income. As a standard practice, they typically request two years' worth of tax returns to confirm the stability of your net income over time. If you can provide more, it's even better.

Jesse Gonzalez, a mortgage broker at North Bay Capital in Santa Rosa, California, suggests that some self-employed individuals may consider reducing their tax deductions as they embark on the homeownership journey. While this may reduce short-term tax benefits, it simultaneously increases your net income, potentially enhancing your qualification for a higher loan amount when you embark on your house-hunting adventure.

2. Amplify Your Savings and Elevate Your Credit Score

While every prospective homeowner should prioritize their credit score, it assumes even greater significance for the self-employed. Lenders perceive your credit history as an indicator of your commitment to repaying the loan, especially during financial downturns. Therefore, make it a priority to consistently make monthly payments on time, well above the minimum required. Simultaneously, focus on reducing your debts as much as possible. In addition to your credit score, channel your efforts into building your savings for the down payment. Although 20% of the purchase price is typically considered ideal, demonstrating the ability to contribute more can position you as a more secure investment.

3. Foster a Relationship with a Local Lender

While large financial institutions may offer marginally lower interest rates, self-employed individuals often find it more advantageous to seek out local lenders. According to Christopher J. Mayer, the Milstein Professor of Real Estate at the Columbia Business School, local institutions tend to be more hands-on and flexible, catering to non-standard financial profiles.

However, don't wait until you're ready to request a pre-approval to establish this relationship. Start today. Holding other accounts at the same bank not only builds trust but also provides you with more options in the future. For instance, selecting a portfolio loan, where multiple loans are bundled together, can enhance your chances of securing a mortgage at a favorable rate.

Feel free to reach out to Scott and the Smolen Team if you have any questions or need a referral to a reputable local lender. We're here to guide you on your journey to homeownership!


Sept. 22, 2024

Is It Time to Downsize? 10 Signs That Say Yes

While living in a spacious home has its perks, there comes a point when downsizing makes more sense. Downsizing is a significant part of real estate business, particularly for clients who are overwhelmed by the upkeep of a large home. Timing is critical, as waiting too long to downsize can lead to financial losses and challenges, especially as health issues arise. Knowing when to make the move is crucial. Downsizing at the right time can prevent financial strain and ensure a smoother transition into a more manageable living space. To help you recognize the signs, here is a list of 10 indicators that it might be time to consider downsizing.

When Do Most People Downsize?

Downsizing is a common choice among empty nesters and retirees. According to the National Association of Realtors (NAR), buyers aged 59 to 68 accounted for 19% of recent home purchases, while those aged 69 to 77 made up 12%. Baby Boomers often seek smaller, more manageable homes closer to family. But downsizing isn’t just for older generations; younger homeowners are also realizing the benefits of a smaller home.

Here are 10 signs that it might be time for you to downsize:

1. Your Monthly Housing Costs Exceed 30% of Your Income

Housing affordability has become a major issue. In 2022, 22.4 million renter households spent more than 30% of their income on rent and utilities, with 12.1 million facing severe financial strain. If your housing expenses are consuming too much of your income, it might be time to consider a smaller home with a more affordable mortgage. Downsizing can reduce not just your mortgage payment, but also utility costs, property taxes, and maintenance expenses.

2. Your Budget Leaves Little Room for Extras

If you’re dipping into your savings just to cover your housing expenses, it’s a clear sign that you should downsize. Moving to a smaller, less expensive home before retirement can free up significant funds. By reducing your housing costs, you can increase your financial flexibility, allowing you to enjoy your retirement years more fully.

3. Home Maintenance Feels Overwhelming

As you age, maintaining a large home can become physically and financially burdensome. Tasks like mowing the lawn, shoveling snow, and making repairs can be challenging. Downsizing to a smaller, low-maintenance home can help you avoid these challenges and save money on upkeep.

4. Your Home No Longer Fits Your Needs

Many seniors find that their longtime home no longer suits their needs. Stairs, steep driveways, and large lawns can become obstacles. A one-story home with accessible features, such as wide hallways and walk-in showers, may be a better fit. Planning ahead and finding a home that accommodates your needs can make aging in place more comfortable.

5. You Feel Isolated in Your Neighborhood

If you’re the oldest resident in your neighborhood, you might feel increasingly isolated as younger families move in. Moving to a retirement community can provide a built-in social network and access to activities, support, and security, which can improve your quality of life and prevent loneliness.

6. You Need to Tap into Your Home Equity

For many seniors, home equity is a significant financial resource. Downsizing to a less expensive home can free up equity and reduce your monthly housing costs, providing you with a steady stream of income for your retirement years.

7. Your Job or Family No Longer Ties You to a Location

Retirees and remote workers often find they have more flexibility in where they live. If your job or family no longer ties you to your current location, downsizing and moving to a more affordable area could be a smart financial move.

8. You Have Unused Space

If you have rooms or amenities in your home that you rarely use, such as extra bedrooms or a home office, downsizing could be a practical choice. Selling a larger home with these features can attract buyers and provide you with funds to purchase a smaller, more efficient property.

9. You Want to Be Closer to Family

Many seniors choose to move closer to their adult children and grandchildren. Downsizing to a condo or a home in a retirement community can make it easier to travel and visit family, while also freeing up resources for other activities.

10. You’re Ready for a Lifestyle Change

Downsizing isn’t just about reducing your living space; it’s also about embracing a new lifestyle. Whether you’re looking to move into a retirement community, live with family, or even take up life on the road in an RV, downsizing can open up new possibilities and reduce financial stress.

Ready to Downsize? We Can Help!

Downsizing offers many benefits, from financial savings to a simpler lifestyle. If you’re considering making this move, planning is key. To discuss your options and find the perfect home that fits your needs, get in touch with Scott and the Smolen Team today!


Sept. 20, 2024

A Complete Guide to Understanding Mortgage Interest

Securing a mortgage involves repaying the lender for the funds borrowed, typically accompanied by interest charges. Various factors, including credit score, income, loan amount, and broader economic conditions, influence mortgage rates. Here is a detailed breakdown of how mortgage interest functions and its implications on different types of loans.

What Constitutes Mortgage Interest?

Mortgage interest represents the cost of borrowing money from a lender, expressed as a percentage. Grasping mortgage rates is pivotal during the homebuying process, as it directly impacts the overall cost of your mortgage.

Typically, shorter-term loans, like 15-year mortgages, boast lower interest rates but higher monthly payments. Conversely, longer-term loans, such as 30-year mortgages, feature higher rates but lower monthly payments due to the extended repayment period. Despite lower monthly payments, shorter-term loans generally entail lower total interest costs.

Understanding Mortgage Interest Dynamics

Your mortgage interest is calculated as a percentage of your outstanding balance. As you make monthly payments according to your loan's amortization schedule, a portion goes towards reducing the principal amount borrowed, while the remainder covers interest expenses. Over time, as your loan matures, a larger portion of your payment is allocated to principal reduction, gradually reducing the interest component.

Illustrating Mortgage

Interest Rates For instance, consider a scenario where you are purchasing a $400,000 home with a 20% down payment, resulting in a $320,000 mortgage at a fixed rate of 6.75%. With this setup, your monthly payment would amount to $2,076, excluding additional expenses like insurance and taxes.

Different Types of Mortgage Loans

When selecting a mortgage, borrowers must choose between fixed-rate and adjustable-rate mortgages, each with unique implications:

  • Fixed-Rate Mortgages: These mortgages feature a consistent interest rate throughout the loan term, resulting in stable monthly payments.
  • Adjustable-Rate Mortgages (ARMs): ARMs initially offer lower introductory rates, which may fluctuate over time based on prevailing market conditions, potentially altering monthly payments.
  • Interest-Only Mortgages: Initially, payments cover only interest expenses, offering lower initial monthly payments. Subsequently, payments increase to include principal repayment.
  • Jumbo Mortgages: These loans exceed local loan limits and often entail stricter eligibility criteria and higher interest rates than standard mortgages.

Understanding APR vs. Interest Rate

While the interest rate denotes the cost of borrowing, the Annual Percentage Rate (APR) encompasses additional expenses like lender fees and discount points, providing a more comprehensive overview of loan costs.

Tips for Securing the Best Mortgage Rate

To secure favorable mortgage terms, consider these strategies:

  • Enhance Credit Score: Strengthen your credit score by timely bill payments and reducing credit utilization ratios.
  • Establish Work History: Consistent employment history strengthens your mortgage application.
  • Increase Down Payment: Larger down payments can secure lower interest rates.
  • Compare Rates: Compare offers to identify the most favorable terms.
  • Explore FHA Loans: FHA loans may offer lower rates for borrowers with less-than-perfect credit.

Consult a Mortgage Broker:

Brokers can assist in finding competitive rates and negotiating terms. Consider Paying Points: Paying points upfront can lower interest rates, particularly for long-term homeowners.

In summary, understanding mortgage interest rates and exploring strategies to secure favorable terms are crucial steps in the homebuying journey. By leveraging these insights, borrowers can make informed decisions and optimize their mortgage financing. If you need a referral to a reputable mortgage lender, reach out to Scott and the Smolen Team!


Posted in Mortgage Tips
Sept. 17, 2024

Top Reasons to Consider Buying a Home Without a Yard

So, you've stumbled upon the house of your dreams, but there's one catch – it doesn't come with a backyard. Should you immediately hit the panic button for your home search? Does it signal a disaster for potential resale value? Not necessarily. According to real estate experts, there are three compelling reasons why a house without a yard might still be the perfect home for you.

1. No Need for the Outdoor Space

Real estate professionals, like Associate Broker Lindsay Barrett from New York, assert that the absence of a yard isn't a deal-breaker if you have no intention of using it. "The reality is, a lot of people don't ever use it," she points out. For instance, if you already own another property, like a vacation home, with ample outdoor space, you might not miss a yard in your primary residence." Elena Maestrone, a licensed agent with Tom Crimmins Realty in New York, seconds this perspective. She believes that most homebuyers have a clear vision of what they want in a home, and a yard doesn't always top the list. Some buyers might even overlook the absence of a yard if they frequently spend time with a family member living in the area who has a yard with amenities like a pool.

2. It's Not All About Resale Concerned about how a yard less home will perform on the resale market? Maestrone reminds us that while the presence or absence of a yard is considered when evaluating neighborhood comparables, it's just one of several factors considered. These factors include the home's square footage, the number of bedrooms, the quality of finishes, and more.

Barrett acknowledges that a yard less property could potentially impact resale value, depending on the market conditions. However, she also emphasizes that if you love the home and it suits your needs, chances are it will appeal to someone else when it's time to sell. In essence, enjoy your home without losing sleep over resale concerns.

"Pay the right price for the property, and there's no reason to doubt its appreciation potential, matching or coming close to other properties in the area," Barrett advises.

In summary, a yard less home can be an ideal choice, especially if you don't require outdoor space or if you have a deep affection for the property and it aligns with your requirements. While resale value is a factor to bear in mind, it should never eclipse the happiness and contentment your home brings. Whether you're in search of the perfect house, with or without a yard, don't hesitate to get in touch with Scott and the Smolen Team today to find the home that suits you best.


Sept. 15, 2024

Securing a Mortgage When Relocating: Essential Tips for a Smooth Transition

When relocating to a new city, securing a mortgage can feel like one more daunting task on an already full to-do list. However, with proper planning and the right steps, the process can be smoother than you might expect. Whether you’re moving for a new job, to be closer to family, or just for a fresh start, getting a mortgage doesn’t have to be complicated. Let’s dive into some tips that can make your mortgage move stress-free.

Get Pre-Approved with a Lender First

One of the first things you should do when relocating is to get pre-approved by a lender. You don’t need to be physically present in your new state to start this process. Gather your financial documents, including your W2s or 1099s, pay stubs, and bank statements, and submit them to a lender licensed in your new state. If you’ve already accepted a new job, include your offer letter or employment contract as well.

Pre-approval gives you a clear picture of what you can afford and helps avoid any surprises down the road. Many lenders offer online and mobile platforms that allow you to complete the process without even stepping into an office. With pre-approval in hand, you can start house hunting with confidence.

Emphasis on Employment

When applying for a mortgage, especially while relocating, steady employment plays a significant role. Lenders typically like to see at least two years of stable work history. If you’re simply transferring your current job to a new location or working remotely, this won’t pose any issues. However, if you’re starting a new job, there are a few things to keep in mind.

Getting a Mortgage with a New Job

If your new job is within the same field, lenders usually won’t have concerns as long as it doesn’t negatively impact your income. For example, moving from a marketing position in one company to a similar role in another won’t raise red flags, especially if your income remains stable or increases. A signed offer letter or employment contract can often be used as proof of income in place of pay stubs.

However, if you’re transitioning into a new career field, or taking time to job hunt, lenders will dig deeper into your future employment plans. In such cases, having a solid savings cushion is essential to cover living expenses while you build employment history. Additionally, if you’re relocating with a spouse or partner who has stable employment, they can act as a co-borrower to increase your chances of loan approval.

Don’t forget to consider the cost of living in your new area. A new job may pay more, but housing costs in your new city could also be higher. Be sure to study up on your new market to understand what you can comfortably afford.

Military Moves

Active-duty military members have unique benefits when it comes to home buying. If you’re relocating due to military orders, you likely already have the employment stability needed for mortgage approval. A VA loan offers incredible advantages, including no down payment requirements, making it easier to buy a home. Plus, relocation assistance programs (RAP) offered by your branch can help cover moving costs and other expenses.

For retired military members, VA loan benefits still apply even if you’re relocating. However, lenders will want to see your retirement income or new employment details to complete the mortgage process.

In Conclusion

Relocating can feel like a whirlwind of change, but with the right approach, getting a mortgage doesn’t have to add to the stress. By getting pre-approved, understanding how your job situation affects your loan options, and tapping into resources like VA loans for military personnel, you can simplify the process and focus on settling into your new home. Ready to take the next step? Reach out to Scott and the Smolen Team for guidance on securing a mortgage and making your move a success!